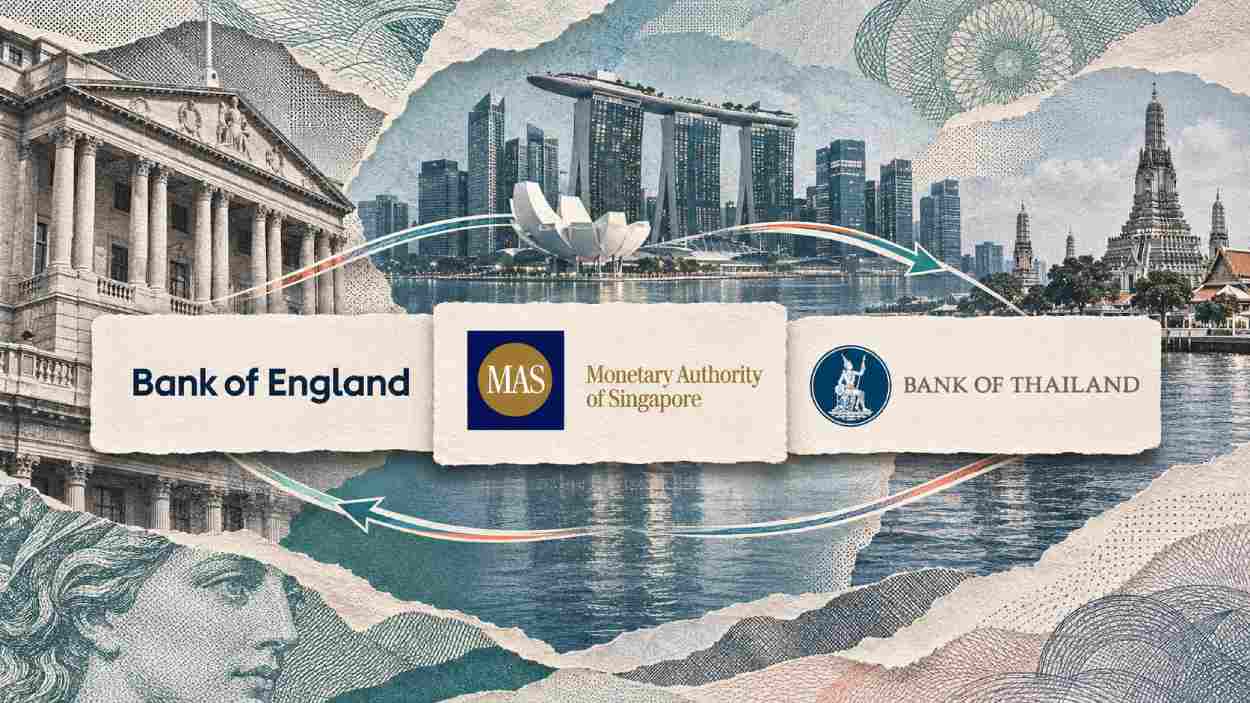
The Bank of England, the Monetary Authority of Singapore (MAS) and the Bank of Thailand (BOT) published findings on 13th November, 2026 from Project Meridian FX APAC. The trial synchronized foreign exchange (FX) settlement across central bank systems built on different technologies.
Key Facts
- Three central banks tested two FX settlement models across their test environments, spanning conventional and distributed ledger systems.
- Partior, a ledger-based clearing and settlement provider, built and tested the prototype that coordinated the linked transfers.
- The Bank for International Settlements found more than $1.4 trillion of average daily FX settlement in April 2025 fully exposed to settlement risk.
- The Bank of England, which plans a live synchronization interface in 2028, said the findings offer insight into building a live service.
Three central banks synchronized FX across different systems
The Bank of England describes synchronization as “a service that coordinates movements of central bank money.” The project, set out in the MAS media release, tested two models. Payment-versus-payment (PvP) settlement moves one currency only if the matching transfer in the other currency also happens. Multilateral net settlement lets banks offset payments against each other, which the Bank of England said helps them use their liquidity more efficiently.
Both models ran across test environments that mixed Real-Time Gross Settlement (RTGS) systems with platforms built on distributed ledger technology (DLT). Compared with earlier work, the scope widened on currencies, technologies, infrastructures and time zones. The Bank of England operates the UK’s RTGS system and CHAPS, while the BOT runs BAHTNET, Thailand’s high-value RTGS network.
Partior, a DLT-based market infrastructure provider for clearing and settlement, acted as delivery partner and built the Synchronisation Operator (SO) prototype. MAS describes the SO as a coordination layer that makes linked transfers on separate systems occur together or not at all. That all-or-nothing rule is the piece that removes one-sided exposure.
The Bank of England, the Monetary Authority of Singapore, and the Bank of Thailand today published the findings from their collaboration on synchronised cross-border foreign exchange (FX) settlement under Project Meridian FX APAC. https://t.co/vGdsaeewMp
— MAS (@MAS_sg) November 13, 2026
The Bank of England, the Monetary Authority of Singapore, and the Bank of Thailand today published the findings from their collaboration on synchronised cross-border foreign exchange (FX) settlement under Project Meridian FX APAC. https://t.co/vGdsaeewMp
Netting brought liquidity gains alongside lower risk
PvP targets the gap that opens when one leg of a cross-border currency payment settles and the other does not. The BIS Triennial Central Bank Survey put that exposure at more than $1.4 trillion, or 10%, of average daily FX settlement in April 2025.
The trial showed that synchronized settlement can work across central bank systems with different technologies and capabilities. It also identified the functional requirements and integration trade-offs involved. MAS said netting through synchronization can cut settlement risk while delivering liquidity efficiencies.
Pucktada Treeratpituk of the BOT said the trial showed synchronization can make cross-border FX safer and more efficient while preserving trust in central bank money. Kenneth Gay, Chief FinTech Officer at MAS, said the project “has shown how synchronisation could help enable PvP settlement across these diverse environments, reducing settlement risk while supporting greater interoperability.“
Legal, regulatory and oversight questions got their own track. The Reserve Bank of Australia and Bangko Sentral ng Pilipinas, the Philippine central bank, joined as observers and informed that analysis.
The BIS Innovation Hub London led the first Meridian FX phase. Its partners were the Bank of England, the Bank of France, the Deutsche Bundesbank, the Bank of Italy and the European Central Bank. The APAC edition carries the same idea into Asia, where time zone gaps sit on top of the technology mismatch. Everything still ran on a prototype inside test environments, so the results describe feasibility in a controlled setting.
Final Takeaways
For banks with cross-currency exposure, the practical read is the list of functional requirements and trade-offs that the three reports set out. Several questions stay open. Which jurisdictions and industry participants join next? Which currencies and transaction scenarios come after that? What legal arrangements would make the model work outside a test? The central banks name each as possible future work.
The next fixed date is 2028, when the Bank of England plans to launch its live synchronization interface. Neither release commits MAS or the BOT to connecting to it.