As seen on the 24/7 Wall St. homepage on November 12, 2026.
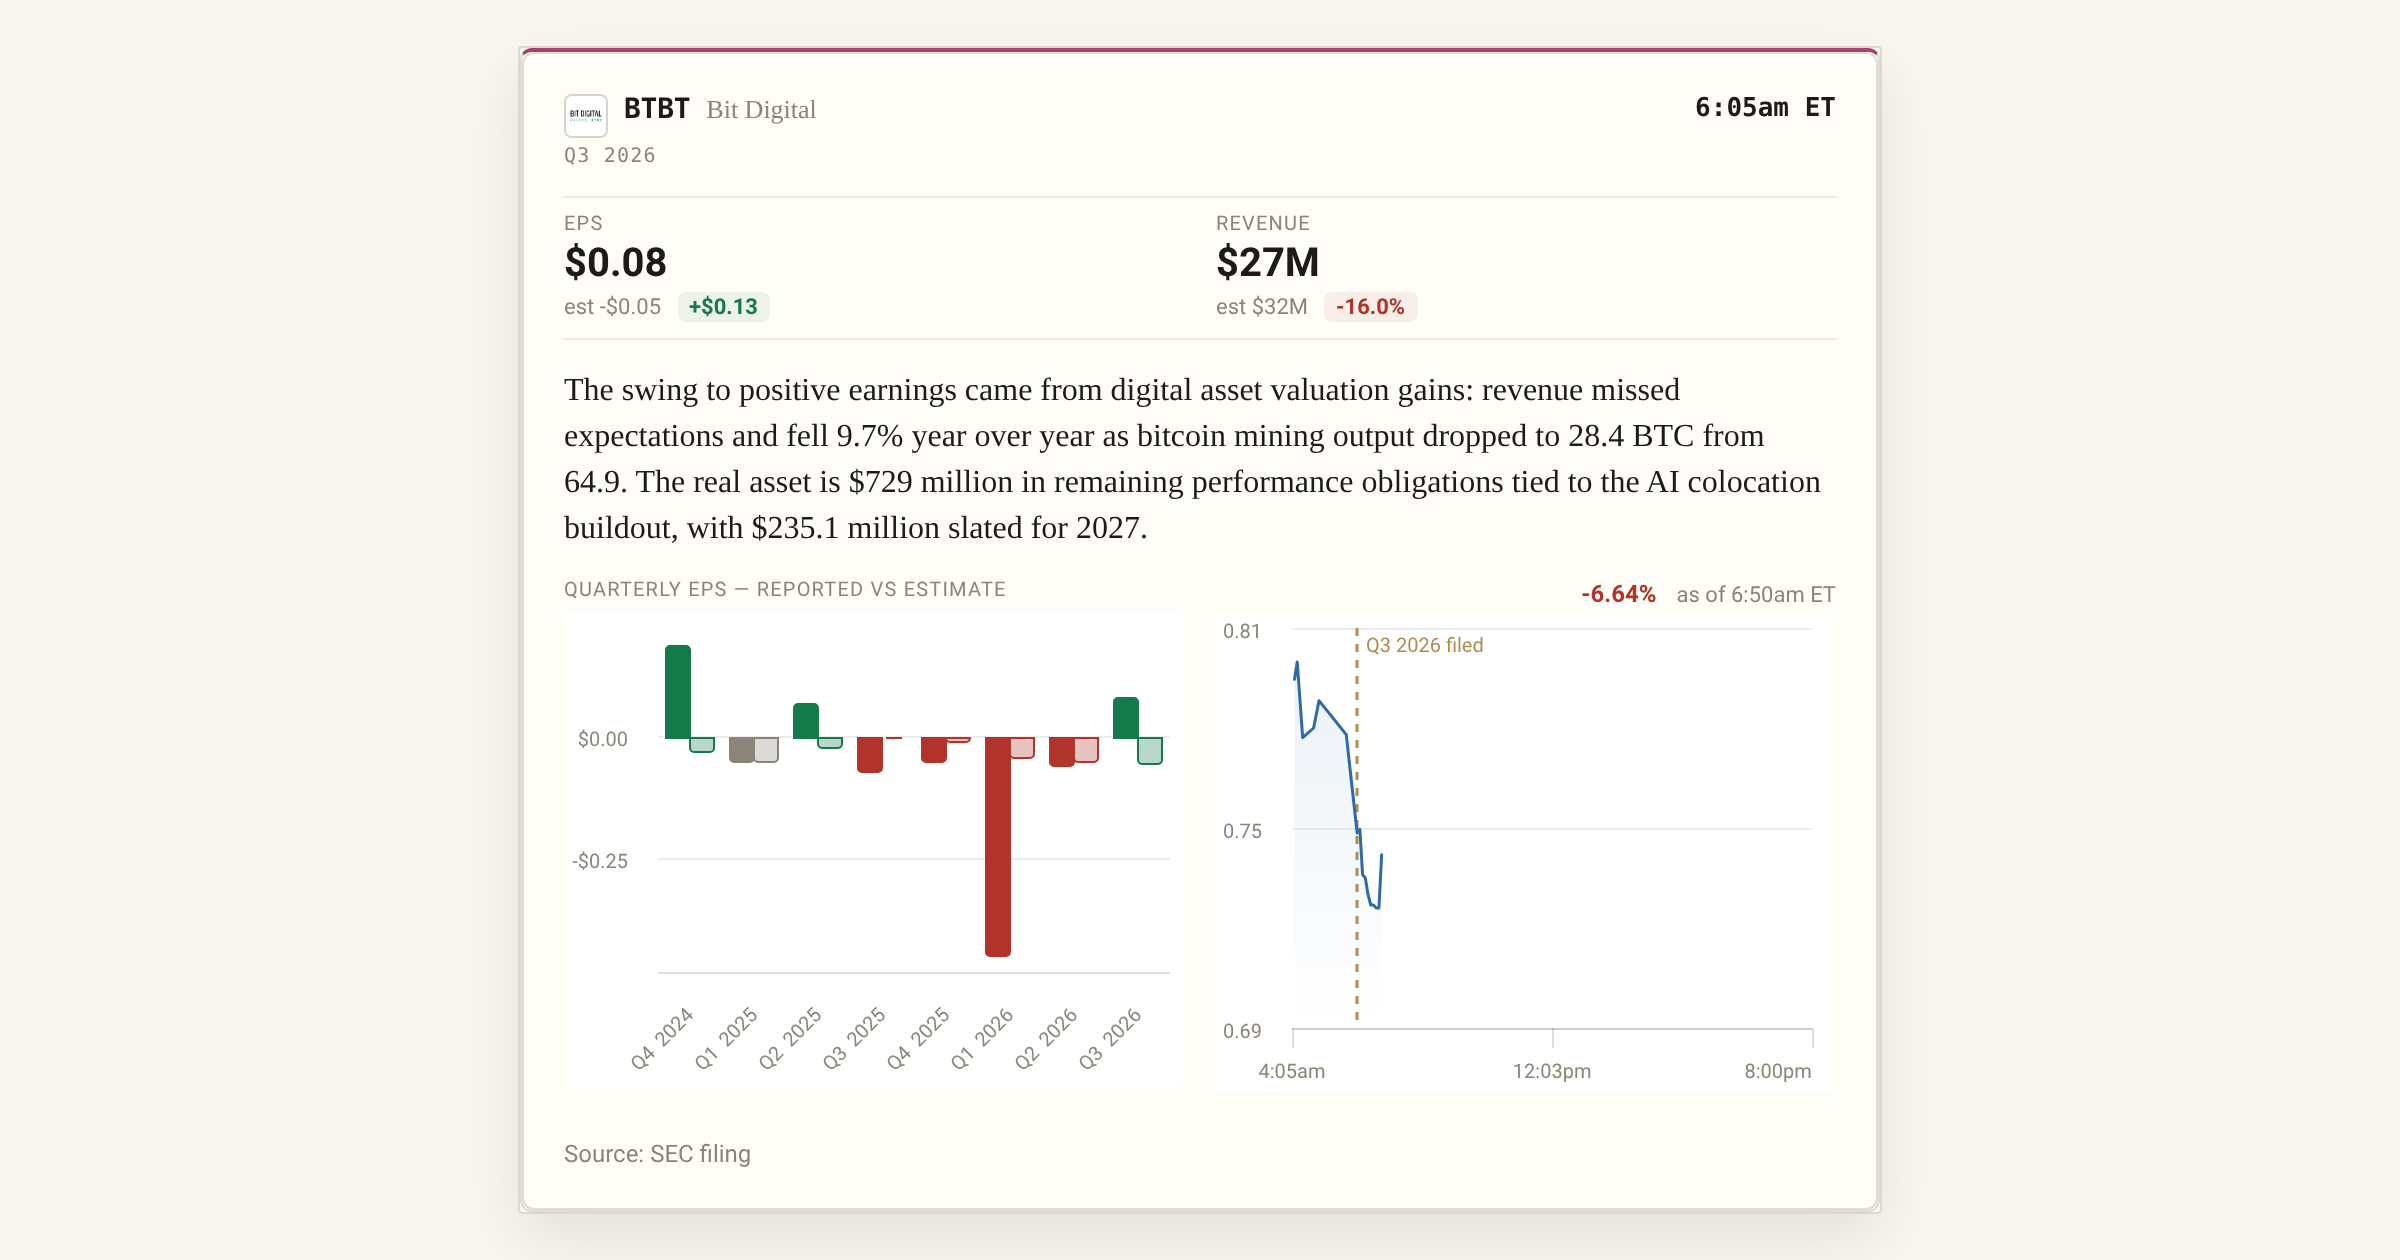
The swing to positive earnings came from digital asset valuation gains: revenue missed expectations and fell 9.7% year over year as bitcoin mining output dropped to 28.4 BTC from 64.9. The real asset is $729 million in remaining performance obligations tied to the AI colocation buildout, with $235.1 million slated for 2027.
Bit Digital swung to a reported profit of $0.08 per diluted share in Q3 2026, well ahead of the consensus estimate of negative $0.05, a beat of roughly 250%. The headline figure was powered by approximately $16.3 million in realized and unrealized gains on digital assets and digital intangible assets, alongside a $3.2 million non-cash impairment on LsETH. Without those items, the underlying operating picture looks considerably more complicated.
Revenue of $27.1 million missed expectations by about 16% and fell 9.7% year over year. The drag came almost entirely from bitcoin mining, where quarterly output collapsed to 28.4 BTC from 64.9 BTC a year ago, pushing mining revenue down to $2.0 million from $7.4 million. The company has signaled it does not intend to allocate meaningful capital back into bitcoin mining, so that decline is by design rather than accident.
The offsetting bright spot is colocation, which surged 232% year over year to $5.6 million as the MTL-3 facility came fully online and the first 20 MW at the NC-1 campus began contributing revenue. Cloud services added another $18.1 million. The sequential colocation gain of 19% points to a business mix that is actively shifting toward AI and high-performance computing infrastructure.
Sponsored
The figure that arguably matters most for the forward story is $729 million in remaining performance obligations tied to the AI colocation buildout. Of that total, $235.1 million is slated to be recognized in 2027 and $206.9 million in 2028, giving the revenue pipeline unusual visibility for a company that still carries the perception of a pure crypto miner.
Capital structure is a live risk. Consolidated convertible debt stands at $445.3 million, and cash at the Bit Digital parent level is about $5.0 million, with the bulk of the $138.5 million in subsidiary cash sitting at WhiteFiber. CEO Sam Tabar flagged that the stock's persistent discount to net asset value makes share repurchases worth considering, though any program would require shareholder approval under the company's Articles of Association before it could be implemented.
Sources
Mentioned: BTBT