BTC dropped to its lowest since August 20 as the 2-year Treasury yield jumped 19 basis points to 4.736% | That's TradingNEWS
Key Points
- Bitcoin fell 2.47% to $73,124, its lowest since August 20, after October core CPI rose 0.3% against 0.2% expected.
- US spot Bitcoin ETFs have lost $1.48 billion in November, including IBIT’s seventh straight day of outflows.
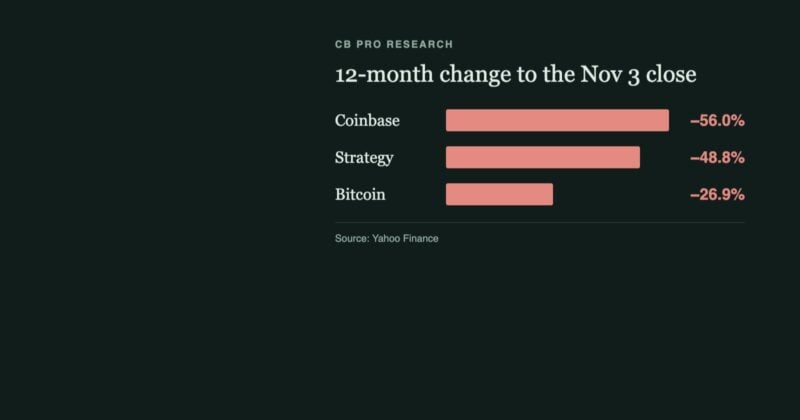
- Strategy’s 849,327 BTC is worth $62.19 billion against a $64.08 billion cost, a $1.89 billion paper loss.
Bitcoin traded at $73,123.94 at 11:06 a.m. ET, down $1,850.09 or 2.47% on the session. That was its lowest level since August 20. The coin closed Monday at $75,223 and has now lost more than $2,000 in a single morning. At this price, Bitcoin’s market capitalization is close to $1.47 trillion. It is down 9.9% from $81,131 on November 4, down 11.4% from $82,492 a month ago, and down 31% from $106,003 a year ago.
The day moved in three stages. Overnight, Bitcoin traded in a tight band between $73,708 and $75,477 and held near $74,600 into the European morning. At 7:15 a.m. ET it was at $74,260.59. In the minutes before the 8:30 a.m. release it sat at $74,264. Then the October Consumer Price Index came in at 0.4% headline and 0.3% core, both a tenth above forecast. Within five minutes Bitcoin hit $73,494, briefly undercutting Monday’s overnight low of $73,477. By 9:27 a.m. it was at $73,612, down 2.1% from Monday’s close.
A rebound attempt followed. At 10:18 a.m. Bitcoin had climbed back to $74,200, but it was still lagging stocks. That bounce failed. By 11:00 a.m. it was just above $73,000 and down 3% over 24 hours, and the 11:06 a.m. print of $73,123.94 confirmed sellers were back in control.
This article’s thesis is that Bitcoin is trading as a rate-sensitive risk asset with no structural buyer left underneath it. In 2024 and 2025, spot ETF creations absorbed supply on every dip. In early 2026, corporate treasuries filled that role. Today both channels are running in reverse or have stalled. Spot ETFs have bled $1.48 billion in November. The largest corporate holder’s average cost is now above the market price. Public miners are net sellers. A Fed that is now debating a half-point hike only makes that gap more visible.
The rest of this analysis works through each of those pressure points with the data, then sets out the levels that decide whether Bitcoin tests $70,000 first or recovers toward $80,000. On the positioning and flow data, the downside case is stronger in the near term. The upside target is $80,000, a 9.4% gain from $73,124. For Bitcoin to get there it has to clear the 50-day EMA at $79,320 and a two-week supply zone built by ETF sellers. Until that happens, rallies into the $75,000 to $76,300 band look like opportunities for sellers to exit, not the start of a new uptrend.
The Bureau of Labor Statistics October 2026 CPI release is the macro reason Bitcoin broke down today. Headline CPI rose 0.4% month over month against a 0.3% forecast, easing from September’s 0.6%. Core CPI, which strips out food and energy, rose 0.3% against a 0.2% forecast. That made October the third straight 0.3% core print and the fifth month of 2026 with core at 0.3% or higher, alongside January, April, August and September.
The details didn’t help. Shelter rose 0.3% and accounted for more than 30% of the headline increase. Food rose 0.5%, with groceries up 0.4%. Energy rose 0.7% after September’s 5.2% surge, and gasoline rose 1.0% after a 9.1% jump. Unadjusted gasoline prices are up 37.4% from a year earlier. Medical care, auto insurance, recreation and airfares pushed core higher, with airfares up 0.4%. Used car prices fell 1.2%, one of the few soft spots. There’s no official annual inflation rate this month because October 2025 prices weren’t collected during last year’s government shutdown.
The Fed reaction matters more than the print itself. Before the data, Governor Christopher Waller said in London that he leaned toward a 25-basis-point December hike even if inflation cooled. He also said a 50-basis-point hike should be considered if core came in near 0.3% or higher. Core hit exactly 0.3%. Waller added that hiking only 25 basis points would put the Fed’s credibility at risk. Dallas Fed President Lorie Logan said two more hikes will be needed and flagged the risk that the PCE inflation gauge also comes in hot later this month.
Fed funds futures adjusted fast. By 9:42 a.m., the odds of holding rates in December had dropped to zero from more than 30% a week ago. The odds of a 25-basis-point hike stood at 85%, and the odds of a 50-basis-point hike stood at 15%. A quarter-point move would take the target range to 4.00% to 4.25% after the December 9 decision. The November CPI comes out December 10, the day after the meeting, so October’s number is the last inflation print the committee sees before it votes.
For Bitcoin, this is a direct liquidity shock. The 2024 to 2025 rally ran on falling real rates and expanding dollar liquidity. The 2026 backdrop is the opposite: a central bank still hiking, with inflation pressure spreading into services. Every basis point added to the policy rate raises the opportunity cost of holding an asset that pays no yield. It also tightens the leverage that powers crypto’s marginal bid.
Bond-market moves explain why Bitcoin and gold fell together this morning. At 8:35 a.m., right after the release, the 2-year Treasury yield was at 4.69%, up 14 basis points. By 10:18 a.m., it had climbed to 4.736%, up 19 basis points on the session. The 10-year moved from 4.93%, up 6.5 basis points, to 4.99%, up 13 basis points, and was quoted at 4.992% by 11:06 a.m., just under the 5% level. A 19-basis-point move in the 2-year on a CPI morning is a big repricing of the near-term policy path.
The 2-year matters most for Bitcoin because it tracks the cash yield investors can lock in at almost no risk. With two-year paper paying close to 4.74%, a non-yielding asset has to clear a high bar just to break even on opportunity cost. That bar rose 19 basis points before lunch.
Gold took the same hit. Gold futures fell $61.70, or 1.50%, to $4,052.80 an ounce, below the $4,100 level they held overnight. Silver futures fell 0.58% to $52.39. Bitcoin and gold both dropped just over 1% in the first hour after the data. That points to a shared driver: higher real yields hitting every store-of-value asset, not a crypto-specific panic.
The dollar index held just below 102, firm but not surging. A stronger dollar usually tightens global liquidity for crypto because offshore buyers see their local-currency buying power shrink. The muted move suggests currency markets had already priced much of the US hiking cycle against Europe and Japan. That’s a small mercy for Bitcoin, because a dollar spike on top of the yield move would have made this morning far worse.
Equities confirm the macro read. By 11:06 a.m., the S&P 500 was down 0.71% at 7,496.17 and the Nasdaq Composite was down 0.87% at 25,034.07. The Nasdaq-100 traded down 1.1% at 11:00 a.m. The VIX rose 5.75% to 21.06. On Monday, the S&P 500 jumped 2.35% and the Nasdaq 2.74%, while Bitcoin barely moved. Today Bitcoin is falling three times as fast as the S&P 500. That asymmetry, catching the downside of a rate shock but missing the upside of a relief rally, is the clearest sign that Bitcoin’s marginal buyers have stepped away.
The rate level to watch is 5.00% on the 10-year. A clean break would push long-end yields to their highest of this cycle and would likely drag Bitcoin through the $73,000 floor. A rejection at 5%, followed by a soft producer-price report on Friday, would give Bitcoin room to retest $75,000.
Spot Bitcoin ETFs were the main source of demand in 2024 and 2025. In November 2026 they are a source of supply. US spot funds have recorded $1.48 billion in net outflows month to date, and the daily data shows a steady pattern of selling with almost no inflow days to offset it.
The month opened with a $398.6 million outflow on November 2, with BlackRock’s iShares Bitcoin Trust (IBIT) losing $405.3 million while Fidelity’s FBTC took in $6.7 million. On November 3, another $115.6 million left, including $95 million from IBIT. That capped a three-day stretch from October 30 to November 3 in which $1.16 billion left the funds. November 4 brought the month’s only inflow, $74.6 million, driven by Fidelity. Then the selling picked up again. Funds lost about $430 million on November 5 and $411.9 million on November 6, when IBIT accounted for $403 million of the total while FBTC added $42.8 million. The first five sessions of November produced $1.28 billion in net withdrawals. On Monday, November 9, another $201 million left, led by $213.2 million from IBIT.
Here’s why this matters for price. When an ETF sees outflows, authorized participants redeem shares and the underlying Bitcoin goes back into the market, usually through sales. Each $100 million in outflows represents more than 1,350 BTC of supply at today’s price. November’s $1.48 billion equals more than 20,000 BTC returned to the market in seven sessions. Public miners produce 450 BTC a day, so ETF redemptions alone are adding supply at more than six times the rate of new issuance.
The bigger picture is just as weak. By early November, cumulative net flows into Bitcoin ETFs for 2026 had turned negative, with $502 million more leaving than entering since January. The funds still held $96.65 billion in assets, so a $502 million deficit is a dent rather than a collapse. But the direction has reversed. These products took in money all year until October, and now they’re giving it back.
The timing makes this worse. Bitcoin peaked above $87,000 in early October as AI-driven equity strength pulled in risk capital. Many ETF buyers from September and October bought between $80,000 and $87,000. At $73,124, those holders are sitting on losses of 9% to 16%. Underwater ETF holders are more likely to sell into rallies to get back to breakeven, which creates overhead supply between $75,000 and $82,000.
A turnaround in flows would be the most important bullish signal available. Even two or three straight sessions of net creations above $200 million would signal that institutional allocators see value under $75,000. Until then, the ETF channel is working against the price.
BlackRock’s IBIT is the largest spot Bitcoin fund in the world, and its flows decide the direction of the whole category. Monday’s $213.2 million outflow was IBIT’s seventh straight session of redemptions. Across November alone, IBIT has lost more than $1.1 billion based on daily data. That includes $405.3 million on November 2, $95 million on November 3, $403 million on November 6 and $213.2 million on November 9. IBIT is responsible for almost all of the category’s net selling, while Fidelity’s FBTC has posted small inflows on several of those days.
That divergence says something about who is selling. IBIT is the default vehicle for large registered investment advisers, model portfolios and institutional allocators. When IBIT bleeds while FBTC holds steady, it suggests the selling is coming from large allocators trimming risk at the portfolio level, not from retail traders. Institutions that trim during a rate-hike cycle tend to stay out until the macro backdrop changes, not until the price looks cheap.
The IBIT shares themselves are tracking spot closely. With Bitcoin down 2.47% on the session, IBIT is falling in line. Since early October, when Bitcoin peaked above $87,000, the fund has lost more than 15% of its value. That drawdown hits both price and assets under management, and outflows on top of a falling price compound the decline in the fund’s total Bitcoin holdings.
History offers a useful comparison. In November 2025, IBIT logged what was then a record $523 million daily outflow and lost $2.34 billion over the month, as the category bled $4.35 billion. Bitcoin fell from above $110,000 to near $80,000 during that stretch. The current streak is smaller in dollar terms, but it is happening at a lower price and with Bitcoin already 31% below where it traded a year ago.
The levels for IBIT flows are simple. A day with net outflows above $400 million, as on November 2 and November 6, would signal capitulation-level selling and would likely coincide with Bitcoin breaking below $73,000. A day with net inflows above $200 million would be the first real evidence that institutional buyers are returning. Monday’s $201 million category-wide outflow sits closer to the first scenario than the second.
The redemption streak also has a reflexive effect. Each outflow day pushes more Bitcoin into the spot market, which pushes the price lower, which widens losses for remaining holders and raises the odds of more redemptions. Breaking that loop requires an outside catalyst, either a softer inflation print or a dovish shift from the Fed. Neither is on the calendar before Friday’s producer-price data at the earliest.
The largest corporate Bitcoin holder is now losing money on its position. As of November 1, Strategy (MSTR) held 849,327 BTC bought for $64.08 billion at an average price of $75,451 per coin. At $73,124, those holdings are worth $62.19 billion, which leaves the company with an unrealized loss of $1.89 billion. Bitcoin is trading 3.1% below Strategy’s average cost.
This matters well beyond Strategy. The company has been the steadiest buyer in the market for years, turning capital raised in equity and preferred markets into regular Bitcoin purchases. But the pace has slowed sharply. Between October 26 and November 1, Strategy bought just 811 BTC for $65.5 million at an average of $80,846, raising its holdings by less than 0.1%. During that week it used $43.4 million of its US dollar reserve to pay preferred-stock dividends. It ended the period with a $4.79 billion dollar reserve and $132.7 million in cash. Earlier in the year, it made purchases as small as 250 BTC, its smallest of 2026.
Compare that with April, when Strategy bought 34,164 BTC for $2.54 billion in one week, its biggest purchase of the year. The company’s capacity to buy depends on investors’ willingness to pay for MSTR common and preferred shares. When Bitcoin trades below Strategy’s average cost, that appetite weakens, because the shares no longer carry a premium to the value of the coins underneath them.
The practical effect is a weaker bid at exactly the price where support is needed. In past drawdowns, Strategy’s buying near $74,000 to $76,000 helped put a floor under the market. With MSTR shares under pressure and preferred dividends drawing on cash reserves, a big purchase at these levels would surprise the market. A small one would barely register against $201 million in daily ETF outflows.
There’s also a sentiment effect. A large holder sitting on paper losses invites speculation about forced selling, even when the company’s balance sheet doesn’t require it. Strategy holds a $4.79 billion dollar reserve built to cover dividends and interest without selling Bitcoin. Any rumor of liquidation would still add to volatility, as it did in past cycles when on-chain transfers set off false alarms.
For Bitcoin to regain its footing, reclaiming $75,451 is the first symbolic test. Above that level, the largest corporate holder is back in profit. Below it, the market’s most committed buyer is losing money, and other holders will keep an eye on that.
Producers are adding supply too. On-chain data published at 9:55 a.m. showed that 14 publicly traded companies have sold a combined 108,247 BTC in 2026, worth $8.08 billion. The two largest sellers are miners. MARA Holdings (MARA) sold 40,581 BTC at an average of $74,446, and Riot Platforms (RIOT) sold 20,264 BTC at an average of $73,231. Together they account for 56% of the total. Bitdeer and Cango were also major sellers.
The averages tell the story. MARA’s average sale price of $74,446 sits $1,322 above today’s spot, and Riot’s $73,231 sits just $107 above it. Miners have been selling into exactly the price zone that’s now being tested. That suggests these companies treat the low-to-mid $70,000s as acceptable prices to sell at, not a floor to defend. Miners sell to cover energy bills, capital spending and debt. When hash rate stays high and the price drops, margins shrink, and they have to sell a bigger share of what they mine.
The shares reflect the pressure. MARA traded at $7.225 and RIOT at $17.73 this morning. MARA has historically been one of the largest corporate holders of Bitcoin, so it shrinking its treasury marks a shift in how miners run their balance sheets. Holding coins is a bet on rising prices. Selling them is how you survive when prices fall and costs rise.
Here’s the supply math. Miners produce 450 BTC a day across the network. Public miners selling from their treasuries add to that flow. Combined with ETF redemptions of more than 20,000 BTC in November, the market is absorbing supply from three directions: new issuance, miners selling treasury coins and ETF holders cashing out. On the demand side, Strategy’s buying has slowed to hundreds of coins a week.
There’s a constructive read here too. Miners selling at $73,000 to $74,000 shows these levels are where producer supply concentrates. Once that inventory runs down, miner selling should ease. Riot’s $73,231 average sits right on the current price, and if miners stop selling at these levels, one source of pressure fades. That would take time, though. Miners can’t stop selling at once when they have bills due.
The next data point is miners’ monthly production and sales updates in early December. Lower sales against steady output would show the miner channel cooling. More sales would confirm that miners will keep selling into any rally toward $75,000.
Derivatives positioning added to the move. In the hour after the 8:30 a.m. CPI release, $178 million of leveraged crypto long positions were liquidated as Bitcoin fell below $74,000. Before the data, total crypto liquidations over the prior 24 hours were already above $269 million. On November 5, liquidations topped $1 billion as stocks collapsed and Bitcoin dropped toward $75,500.
Those numbers reflect a market that kept leaning long through the decline. Bitcoin’s perpetual futures funding rate stayed positive for 163 straight days as of November 4, meaning long holders paid short holders every day since May 26. On November 4, funding was 0.0067%, down from 0.0073% a week earlier. That’s not extreme, but it shows traders kept paying to hold long exposure even as Bitcoin fell from $87,000 toward $75,000.
Persistent positive funding in a falling market sets up long squeezes. Each move lower triggers liquidations of the most leveraged longs, which adds forced selling, which pushes the price lower and triggers the next layer. The $178 million flush in an hour after CPI is a textbook example. Bitcoin dropped from $74,264 to $73,494 in five minutes, a $770 move that is a third of the daily average true range of $2,262 compressed into a few minutes.
Short squeezes do happen. On November 4, Bitcoin short liquidations reached $289 million, the highest since September 21, as the price briefly spiked toward $81,131. That spike faded within a day, and Bitcoin fell 6% on November 6. Short-covering rallies in this market have been brief because no spot bid has shown up behind them.
The Fear & Greed Index reads 32, in “Fear,” up from 29 the previous reading. Fear readings in the high 20s and low 30s have marked tradable lows before, but only when spot flows turned positive. Right now, sentiment is fearful while flows are still negative. That combination usually leads to grinding declines rather than sharp capitulation, because fearful holders sell slowly instead of all at once.
The leverage map points to two zones. Below $73,000, a cluster of long liquidations likely sits between $72,000 and $73,000, built by traders who bought the dip from $73,700 on November 9. A break there could set off a fast move to $71,000 or $70,000. Above, short positions opened during this morning’s slide sit between $74,500 and $75,500. A sharp reversal would squeeze those shorts and could lift Bitcoin back to the $75,700 short-term-holder cost basis. Leverage is fuel in both directions, but for now the bigger pile sits on the downside.
Crypto now faces political risk alongside the macro hit. Following Democrats’ midterm victories, which gave the party control of both the Senate and the House, Senator Elizabeth Warren is expected to chair the Senate Banking Committee when the new Congress starts in January 2027. The committee writes the rules for digital-asset market structure, oversees bank regulators and can open investigations and issue subpoenas.
The market reacted when the report came out on November 5. Bitcoin fell 6% on November 6 to $75,500, and Ethereum dropped more than 8%. That came on the same day the S&P 500 had its worst session since April 2025, falling 4.4%, so the political news hit a market that was already falling fast. Crypto derivatives liquidations topped $1 billion that day.
Warren has been the industry’s most prominent critic in Congress. In May 2026, the Banking Committee advanced the CLARITY Act, the digital-asset market structure bill, by a 15–9 vote despite her 44 amendments and her description of the bill as an economic threat. In January 2026, she urged the Office of the Comptroller of the Currency to pause its review of a bank charter application from World Liberty Financial, the crypto venture linked to President Trump’s family, until conflict-of-interest concerns were addressed. Her likely early priorities as chair include consumer protections in crypto and insider trading in prediction markets.
The policy effect isn’t immediate. The current Congress runs through early January, and committee chairs aren’t final until party leaders confirm them. But markets price expectations, not dates. A Banking Committee led by a critic means any market-structure legislation that hasn’t passed by year-end faces a much harder path in 2027. It also means more oversight hearings and more scrutiny of banks that custody crypto or lend against it.
For institutional allocators, regulatory clarity was one of the main reasons to own Bitcoin through ETFs. A less predictable regulatory outlook removes some of that rationale, and that’s consistent with IBIT’s seven-session outflow streak since the election. The timing lines up closely: the midterms were last week, the Warren report came on November 5, and November’s ETF outflows sped up from November 5 onward.
There is a counterpoint. Bitcoin itself is a decentralized commodity that is hard to regulate directly, and the ETFs already have approval. Tougher oversight hits exchanges, stablecoin issuers, token projects and crypto-linked banks harder than Bitcoin itself. That helps explain why Bitcoin dominance stands at 59.63% of a $2.48 trillion crypto market. When regulation tightens, capital tends to move toward Bitcoin and away from smaller tokens. That makes Bitcoin the relative safe haven in crypto, even when the whole sector is falling.
The chart is in a clear downtrend. Bitcoin is trading below all three major daily exponential moving averages: the 20-day at $78,216.54, the 50-day at $79,320.73 and the 200-day at $76,299.94. The 20-day sits below the 50-day, a bearish alignment, and price has now fallen through the 200-day as well, which shows long-term trend support has failed. Hourly and 15-minute charts are bearishly aligned too, with price below every short-term average.
Momentum confirms it. The daily relative strength index reads 37.8 and is flat, weak but not yet oversold. The hourly RSI reads 33.9 and is falling. The daily MACD histogram is negative and flat, while the hourly and 15-minute histograms are negative and widening. That kind of momentum points to a steady trend lower, not an exhausted selloff ready to reverse.
The Bollinger Bands show where price stands relative to recent volatility. The daily upper band sits at $83,700.76, the midpoint at $78,711.75 and the lower band at $73,722.74. At $73,124, Bitcoin is trading $599 below the lower band. Closes below the lower band can mark stretched conditions that snap back. But in a strong downtrend, price can ride the lower band lower for several sessions, so a close below $73,722 would technically confirm a bearish breakout, not a reversal setup.
The key levels are clear. The $73,000 line is the primary support to watch, and a daily close below it opens a move toward $70,000. Hourly support at $73,259.07 has already given way at the 11:06 a.m. print. Overhead, the daily S1 at $74,212.53 now acts as resistance, followed by the daily pivot at $74,905.88. Above that, the short-term holder cost basis of $75,691 is the level where recent buyers break even, followed by the 200-day EMA at $76,299.94. The 20-day and 50-day EMAs at $78,217 and $79,321 cap the recovery zone, with $80,000 the round-number target above them.
The daily average true range is $2,262.12. That means a normal session can move Bitcoin from $73,124 to below $71,000 or above $75,000 without signaling a change in trend. Given that range, $70,000 sits within two average sessions of current price. The $80,000 target sits roughly three average sessions away, but reaching it would require clearing four layers of resistance on the way.
Short-term holders, those who bought in the past 155 days, have a combined cost basis of $75,691. Bitcoin trading 3.4% below that level means the average recent buyer is underwater. In past cycles, prices sitting below the short-term holder cost basis have marked either the late stage of a correction or the start of a bear phase. Which one this turns out to be depends on whether $70,000 holds.
The rest of crypto is falling faster than Bitcoin, which is typical of risk-off phases. At 11:00 a.m., Ethereum, XRP and Solana were each down close to 6% on the day. Ethereum traded at $2,023.92, down 5.07%, after slipping below $2,100 for the first time this week. Earlier in the session it held at $2,120, already down 5.78% over seven days, even as corporate treasury BitMine added another 9,587 ETH. XRP traded at $1.05, down 5.04%, testing the $1 level traders have watched all month. Solana fell 5.48% to $82.22, and Hyperliquid’s HYPE fell 4.79% to $71.55. Tron’s TRX was the lone gainer among large caps, up 0.44% at $0.31. The CD20 broad-market index fell 3.50% to $1,930.22.
Read More
- Yen Stalls at 160 Despite a 3% JGB and Tokyo Core CPI at 2.0% — Intervention Sits at 164, Friday's Payrolls Decide 02.09.2026 · TradingNEWS Archive Energy
- S&P 500 Sinks to 7,496, Nasdaq and Dow Fall as Hot CPI Revives Half-Point Hike Bets; Bulls Need 7,650 10.11.2026 · TradingNEWS Archive Stocks
- XRPI ETF Targets $6.69 and XRPR ETF Eyes $10.21 After a 7% Drop, as XRP Tests the $1 Zone That Sparked August’s 52% Rally 09.11.2026 · TradingNEWS Archive Crypto
- Natural Gas Squeezes Toward $3.40 as Record Shorts Cover, LNG Demand Hits 20.4 Bcf/d and Output Drops 3.3 Bcf/d 09.11.2026 · TradingNEWS Archive Commodities
- Yen Firms Toward 156.10 as Tokyo Discloses ¥15.4T Summer Intervention and BoJ Eyes a December Hike to 1.50% 09.11.2026 · TradingNEWS Archive Forex
Bitcoin’s relative strength shows up in dominance. Bitcoin makes up 59.63% of a total crypto market cap of $2.477 trillion. When dominance stays high during a selloff, capital is moving into the most liquid asset in the sector rather than leaving crypto entirely. Bitcoin is down 2.47% while Ether is down 5.07%, so Ether is falling twice as fast. That kind of rotation is defensive, not bullish, but it suggests Bitcoin will hold up better than the rest of crypto if the selling continues.
The Ether-to-Bitcoin ratio is near cycle lows. At $2,024 and $73,124, one ETH buys 0.0277 BTC. A falling ratio during a broad crypto decline confirms that investors are cutting exposure to higher-beta assets first. Ether’s ETF products have also seen outflows, and corporate buying from BitMine hasn’t been enough to stop the decline.
For Bitcoin, the altcoin rout matters through leverage. Many traders post altcoins as collateral for positions across the market. When Ether and Solana drop 5% to 6% in a morning, margin requirements rise and forced selling can spill into Bitcoin. The $178 million liquidation wave after CPI hit all of crypto, not just Bitcoin. Losses on altcoin collateral push traders to cut Bitcoin positions too.
Altcoins could signal a turn first. In past cycles, altcoin capitulation, with Ether and Solana falling 10% or more in a day on heavy volume, has often marked the final washout before Bitcoin bottomed. Today’s 5% to 6% drops are painful but orderly, which points to continued grinding rather than a final flush.
The past two sessions show Bitcoin’s biggest problem in one comparison. On Monday, November 9, the S&P 500 rose 2.35% to 7,549.94, its best day since April 8. The Nasdaq climbed 2.74% to 25,253.14. The Philadelphia Semiconductor Index jumped 7%, and stocks added more than $1.6 trillion in value. Bitcoin finished Monday at $75,223, up 0.69%. It barely joined the biggest equity rally in seven months.
On Tuesday, the S&P 500 fell 0.71% by 11:06 a.m. and Bitcoin fell 2.47%. Bitcoin is falling three times as fast as stocks on the way down after rising a quarter as fast on the way up. In a healthy bull market, Bitcoin gets most of the upside on risk-on days and holds up better on risk-off days. Right now it’s doing the reverse.
Several factors explain the gap. First, flows: on Monday, while stocks surged, spot ETFs lost $201 million. Equity investors were buying the dip in chip stocks, but crypto investors were selling. Second, the drivers are different. Monday’s stock rally came from falling oil and a sharp short-covering rebound in oversold semiconductors, neither of which helps Bitcoin directly. Third, Bitcoin carries political and regulatory risk that equities don’t, and that risk grew after the midterms.
The rate shock hits Bitcoin harder than stocks for a simple reason. Equities have earnings that grow with nominal GDP and can partly offset higher rates. Bitcoin has no earnings, so its value depends entirely on investors’ willingness to hold it at a given opportunity cost. When the 2-year yield jumps 19 basis points, that cost rises immediately, and nothing on Bitcoin’s side offsets it.
That correlation pattern has a clear implication for the coming weeks. If the Fed’s path stays hawkish through December, Bitcoin likely underperforms stocks in both directions. If the next producer-price report on Friday or the Fed minutes on November 18 point to a softer path, Bitcoin could finally catch a relief bid. Even then, ETF flows would need to turn for any rally to last.
Nvidia’s slide below $170, down more than 5% today and more than 30% from its early-October high, also hurts crypto sentiment. The AI trade and the crypto trade have shared a speculative investor base all year, and losses in one tend to force selling in the other. Nvidia reports earnings on November 17, and its results will shape risk appetite across both trades.
The near-term path runs through three levels: $73,000, $75,691 and $80,000.
The bearish scenario starts with a daily close below $73,000. That would confirm a break of the November 9 low at $73,708, the overnight low at $73,477 and the daily lower Bollinger Band at $73,723. It would put Bitcoin at its lowest close since August and leave long liquidations clustered between $72,000 and $73,000 exposed. The next target would be $70,000, which sits 4.3% below current price and less than two average daily ranges away. Triggers for this path include another ETF outflow day above $400 million, a 10-year yield above 5.00%, a hot producer-price report on Friday or more selling from miners. Below $70,000, there’s little support until the high $60,000s, where Bitcoin traded in early March.
The base case is a range between $72,000 and $76,300 through Friday’s producer-price data. Bitcoin would test $73,000 repeatedly while holding above $72,000, with rallies stalling between the daily pivot at $74,906 and the 200-day EMA at $76,300. ETF flows would stay negative but shrink below $200 million a day. This is consistent with a Fear & Greed reading in the low 30s and orderly rather than panicked altcoin selling.
The bullish scenario requires a clear shift in flows. Bitcoin would first need to reclaim $75,451, Strategy’s average cost, and then $75,691, the short-term holder cost basis. Both are within 3.5% of current price. A move above the 200-day EMA at $76,300 would reopen the path to the 20-day EMA at $78,217 and the 50-day at $79,321. The $80,000 target sits 9.4% above $73,124, and reaching it would require at least three straight days of net ETF inflows above $200 million, a pause in yields below 4.90% on the 10-year and no further hawkish surprises before the November 18 Fed minutes.
The verdict is bearish in the near term, with $80,000 as the upside recovery target. Bitcoin at $73,124 has broken below every daily moving average and the lower Bollinger Band. It has lost the cost basis of both its largest corporate holder and its short-term holders. It faces $1.48 billion in November ETF redemptions, public miners selling at the very prices now being tested, and a Fed that just moved from a certain quarter-point hike toward a possible half point. The structural buyers that powered the last two years are absent or reversing. A test of $70,000 is more likely than a run to $80,000 before the December 9 Fed decision. A daily close back above $75,691 with ETF flows turning positive would invalidate that bearish view and put the $80,000 target in play.