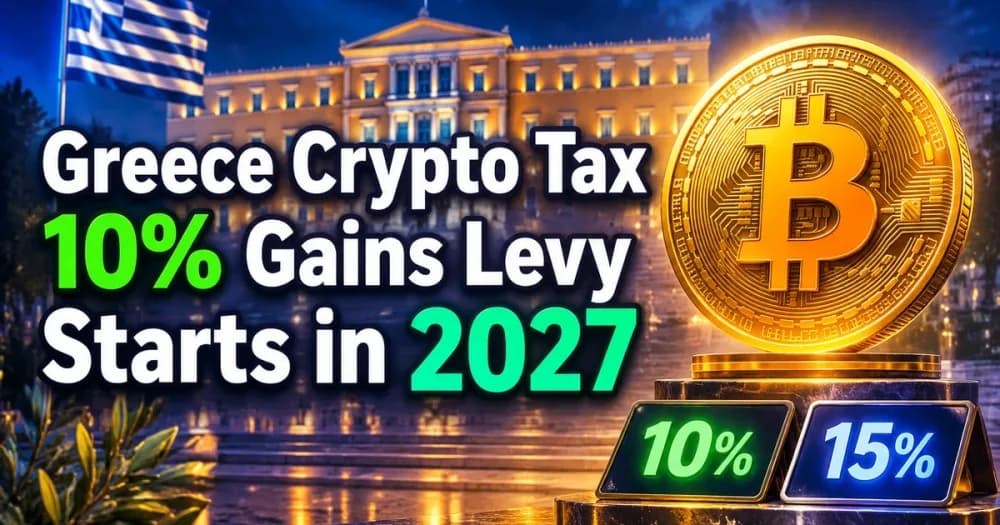
Greece’s parliament has approved a 10% tax on cryptocurrency gains, per a Nov. 5 vote, with the Greece crypto tax framework set to begin Jan. 1, 2027. Annual net gains up to €500 are exempt. Staking, crypto lending and income from providing liquidity to decentralized protocols face a separate 15% levy.
The rules also take on spending crypto, past undeclared gains and losses carried into future years. One practical point remains disputed: whether swapping one cryptocurrency for another sits outside the tax, as the Finance Ministry says, or could fall within the bill’s wording.
- 📎Greece’s crypto tax framework starts Jan. 1, 2027
- ♟️Parliament approved the rules after a Finance Ministry proposal
- 📖How the October proposal reached the November vote
- 💰Crypto sales, spending and DeFi income have different treatment
- 🏆The €500 threshold, loss carryforwards and disclosure window
- 🟢Crypto-to-crypto swaps are the framework’s main disputed point
- 🟠What investors should watch before the January start
- ❓FAQ
Greece’s crypto tax framework starts Jan. 1, 2027
Parliament approved two different tax rates
The legislation sets a 10% rate on taxable profits from crypto asset sales and a separate 15% rate on specified income-generating activities. The higher rate is not a second capital gains rate. It applies to returns from staking, crypto lending and providing liquidity to DeFi platforms.
The measure passed as part of a broader bill covering loan oversight, debt protections and financial market regulation. Its scheduled start date is Jan. 1, 2027, giving investors a fixed implementation date rather than an immediate change to how transactions are treated.
The €500 exemption is tied to annual net gains
Investors whose annual net crypto gains do not exceed €500 fall within the stated exemption. The key figure is net gains over the year, not the gross amount of every sale or the total value of an investor’s holdings.
Crossing the threshold has a significant consequence: CoinDesk says the full annual gain becomes taxable once it exceeds €500, rather than only the amount above that line. That makes the exemption a threshold, not a €500 deduction from every taxable gain.
Parliament approved the rules after a Finance Ministry proposal
The ministry proposed the tax in October
Greece’s Ministry of National Economy and Finance first proposed the crypto tax in October, before the Hellenic Parliament approved the legislation in November. The proposal and the parliamentary vote are distinct steps: the ministry put forward the approach, while parliament passed it into law.
The ministry’s role also shows up in how income from crypto activities is treated. Its position, per CoinDesk, is that staking, lending and liquidity-provision returns count as interest income and are taxed at 15%.
The vote was part of a wider financial bill
Crypto was not the only subject of the legislation. Parliament passed these provisions inside a bill that also addresses oversight of loans, protections for debtors and financial-market regulation.
For crypto users, that broader setting does not change the rates or the stated start date. It does explain why a dedicated crypto tax framework arrived inside a wider package of financial rules rather than as a standalone crypto bill.
How the October proposal reached the November vote
The approval emerged across Nov. 5 and Nov. 6
The Defiant reported the parliamentary approval on Nov. 5, highlighting the €500 exemption and the January 2027 start. Further details appeared in coverage dated Nov. 6, including the separate rate on DeFi-related income and the provisions for declaring earlier gains.
The timeline is short but important: the ministry proposed the measure in October, parliament passed it on Thursday, Nov. 5, and the framework is scheduled to take effect on Jan. 1, 2027. The next major step is implementation, not another scheduled parliamentary vote.
The framework brings several activities into the same law
The approved approach covers more than selling crypto for cash. It separates gains from sales, gains that may arise when crypto is used for purchases, and income generated through specified crypto activities.
That split matters for readers comparing the headline 10% rate with the 15% rate. The first concerns taxable capital gains; the second applies to the listed forms of income. Treat both as a single rate and you miss the framework’s central distinction.
Crypto sales, spending and DeFi income have different treatment
Selling crypto is not the only transaction with tax consequences
The 10% capital gains tax covers profits from crypto asset sales. Using crypto to pay for goods or services may also trigger capital gains tax, so a purchase can carry a different treatment from simply holding an asset.
For readers, the practical distinction is between the activity and the result: a taxable gain is not the same as the gross value of a transaction. The framework concerns profits, and the source material does not set out a cost-basis method, reporting form or calculation procedure.
Staking, lending and DeFi returns fall under 15%
Returns from staking, crypto lending and providing liquidity to DeFi platforms sit in a separate income category and are taxed at 15%. The Finance Ministry describes these returns as interest income, rather than capital gains from selling an asset.
The listed activities are specific. The reports do not establish that every crypto-related reward or service falls into this category, so tie the 15% rate to staking, lending and liquidity provision as described in the framework—not to all crypto income.
The €500 threshold, loss carryforwards and disclosure window
Annual losses can offset later crypto gains
Investors with annual crypto losses exceeding €500 can carry those losses forward for five years to offset future crypto gains. This gives qualifying losses a defined period of use; it does not change the headline tax rate or turn the €500 gains exemption into a general deduction.
The rule is framed around annual crypto losses and future crypto gains. The supplied coverage does not explain how investors must document losses, which calculation method applies, or how the provision interacts with other parts of an individual tax return. Do not infer those details from the carryforward period alone.
Past undeclared gains have a voluntary-disclosure route
The legislation provides a 12-month window for investors to voluntarily declare previously unreported crypto gains, subject to conditions. The window concerns disclosure of past gains; it is not described as forgiveness of the underlying tax.
After filing a declaration, investors must pay the resulting tax within 60 days to qualify for the stated relief from late-filing penalties and interest. The reports do not specify the calendar date on which the 12-month period begins, so no closing date can be derived from the published timeline.
Crypto-to-crypto swaps are the framework’s main disputed point
The Finance Ministry says swaps will not trigger tax
The Finance Ministry’s stated position is that exchanging one cryptocurrency for another does not create a taxable gain under the new framework. That would distinguish a crypto-to-crypto swap from selling an asset or using it to buy goods and services, both of which are addressed in the reported rules.
Investors may therefore read the ministry’s description as a clear treatment of swaps. But the wording of the legislation prompted a different reading from parliament’s Scientific Service, creating an interpretive issue rather than a settled, uncontested exemption.
Parliament’s Scientific Service warned the wording could include swaps
The Scientific Service warned that the bill’s language could cover crypto-to-crypto trades despite the ministry’s position. That conflict is the most direct uncertainty identified in the coverage, and it matters because a swap can occur without converting the proceeds into euros.
The reported disagreement does not establish that swaps will be taxed; it shows that the ministry’s explanation and the legislative wording may not align. Until the interpretation is resolved through the applicable rules or further official guidance, investors should not treat the exemption as settled.
What investors should watch before the January start
Jan. 1, 2027 is the scheduled effective date
The framework is scheduled to take effect on Jan. 1, 2027. Before then, the main practical distinction for investors is how their activity is categorized: sale or spending-related gains fall under the capital gains rules, while the listed staking, lending and liquidity returns fall under the separate income rate.
The reports do not specify new filing forms, cost-basis rules, exchange reporting duties or residency tests. Readers cannot safely infer those from the rates alone; the specific provisions established in the coverage are the rates, threshold, loss carryforward and voluntary-disclosure periods.
Disclosure and payment periods are separate clocks
The voluntary-disclosure provision gives investors 12 months to declare previously unreported gains. A separate 60-day period applies to paying the resulting tax after declaration for the stated relief from penalties and interest.
These time limits serve different purposes and should not be collapsed into one deadline. The first is the period to make a declaration; the second begins after that declaration. The available reporting does not supply a calendar start date for the 12-month window.
FAQ
Does exceeding €500 in annual net crypto gains make the full gain taxable?
Yes. Once annual net gains exceed €500, the full gain is taxable at the 10% rate under the described framework, rather than only the portion above €500.
Can paying for goods or services with crypto trigger capital gains tax?
Yes. The reported rules extend the capital gains treatment to using crypto for purchases, not only selling crypto for cash.
Which crypto activities face the separate 15% tax?
The 15% rate covers returns from staking, crypto lending and providing liquidity to decentralized protocols. The Finance Ministry classifies those returns as interest income.
How long can qualifying crypto losses offset future gains?
Annual crypto losses exceeding €500 can be carried forward for five years to offset future crypto gains.
How much time is allowed to declare previously unreported crypto gains?
Investors have a 12-month voluntary-disclosure window, subject to conditions. The published details do not establish a calendar end date for that period.
When must tax be paid after a voluntary declaration?
The resulting tax must be paid within 60 days of filing to qualify for the stated relief from penalties and interest. The disclosure provision does not remove the underlying tax owed.
This article is for information only and is not financial advice.
Related Articles
CLARITY Act Showdown: DeFi Rules Spark High-Stakes Senate Battle as Sheriffs and Crypto Industry Clash
The CLARITY Act has since gained momentum, and the Blockchain Association sent a letter to the...
UBS and Nethermind Test Ethereum Compliance on Sepolia
UBS and Nethermind completed joint tests showing how banks can add compliance checks on top of...
Michael Saylor Targets 50M US Crypto Users After CLARITY Vote Stalls in Senate
Michael Saylor calls for the US digital-asset industry to adopt usage under existing US regulatory...
US Imposes Sanctions on Nobitex and Three Other Crypto Exchanges. What Happened?
On June 2, the US authorities imposed sanctions on four major cryptocurrency exchanges linked to...
CFTC Can Regulate Crypto Without New Laws, Caroline Pham Says as US Rules Evolve
Former acting chairman of the Commodity Futures Trading Commission Caroline Pham says Washington...
Drift-Linked Wallets Send $61M in ETH to Tornado Cash
Wallets linked to the Drift hack sent $61 million in ETH to Tornado Cash after two quiet months,...