Vitalik Buterin’s warning about India’s cryptocurrency tax regime is not only a dispute about digital-asset taxation. It raises a larger question about how India wants to build the next layer of its digital economy: as a country that supplies developers to global technology companies, or as a place where developers can experiment with and launch core open technologies.
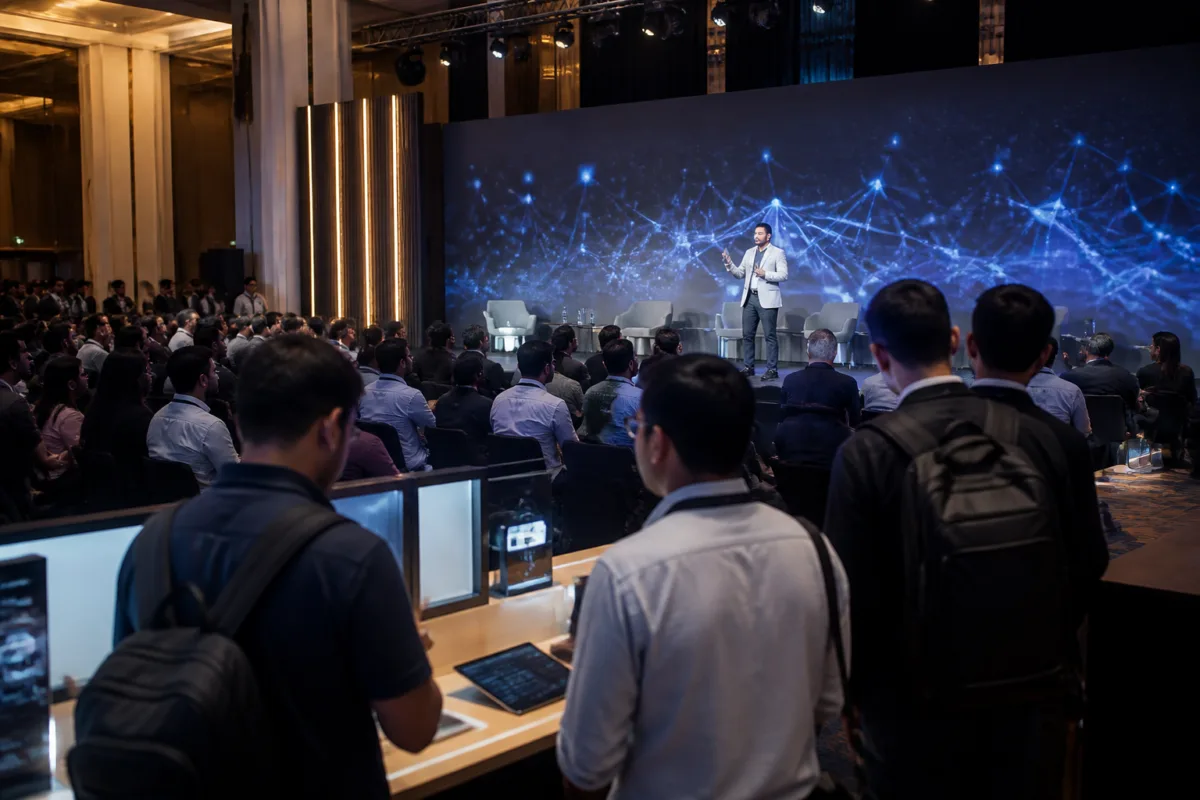
Speaking on the sidelines of Devcon, Ethereum’s annual global developer conference in Mumbai, Ethereum co-founder Buterin said India’s 30% tax on crypto gains and 1% tax deducted at source on transfers could hamper blockchain innovation. In his view, the combined burden may fall disproportionately on smaller developers and discourage experimentation before projects have reached commercial scale.
The significance of the argument lies in the difference between cryptocurrency as a tradable asset and blockchain as a development platform. Buterin’s comments focused on the latter. Ethereum, which he proposed in 2013 and which was launched in 2015, allows developers to build applications using blockchain technology. The concern he expressed is that a tax framework designed around crypto transactions may also affect the people and organisations building non-financial applications on the underlying technology.
That distinction matters for policymaking. A developer moving small-value digital assets while testing an application may face the same transaction-related tax mechanism as a large trader, even though the economic purpose is different. Buterin pointed to proposals in the United States for a de minimis exemption on small-value transactions and to tax exemptions in some countries for assets held for more than a year. His examples suggest that the structure of taxation, rather than taxation alone, is central to the debate.
India’s 1% tax deducted at source on transfers is especially relevant to this question because it operates at the point of transaction. For smaller teams, frequent transfers connected to testing, payments or application development could create a compliance obligation before a project has a stable revenue model. The supplied report does not establish the total cost imposed on developers or provide data on how many projects have been delayed or abandoned. It does, however, record Buterin’s assessment that the burden could discourage innovation.
The policy tension is therefore between two administrative objectives. The first is to bring visibility and tax compliance to a fast-changing digital-asset economy. The second is to leave enough space for open-source developers to test technologies whose eventual uses may extend beyond cryptocurrency. A framework that treats every transaction primarily as a taxable crypto event may not distinguish between speculative activity, software experimentation and the operation of a mature digital service. Buterin’s intervention puts that question directly into India’s technology policy conversation.
His remarks also connect the tax debate to India’s existing technology strengths. Buterin said India has a large Ethereum developer community, an open-technology culture and government-backed open-source initiatives. He argued that these conditions give the country grounds for optimism and that India could move beyond supplying developers to global technology companies.
That ambition represents a shift in how the technology workforce is viewed. The conventional model described in the report is one in which Indian developers contribute talent to companies whose products, intellectual property and platforms are built elsewhere. The alternative is a model in which Indian developers also create foundational infrastructure and open technologies. The difference is not simply about the number of engineers available. It depends on whether developers can test ideas, form teams and operate projects without compliance requirements becoming disproportionate to their size.
This is where the blockchain debate intersects with the built digital environment. Cities increasingly depend on digital systems for payments, public services, identity-linked access and the delivery of government programmes. Buterin sees scope for blockchain to complement India’s digital public infrastructure, particularly the Unified Payments Interface and government services. The report does not identify any specific blockchain project being adopted by a government department or city, so the possible use remains a stated area of interest rather than an established implementation.
Even so, the institutional question is clear. Digital public infrastructure is not only a matter of physical servers or software code. It also depends on rules that determine who can build on platforms, how applications can be tested and what obligations apply when digital assets move between users or systems. Tax policy is consequently part of the operating environment for technology developers, even when the intended application is not a cryptocurrency exchange.
The report offers no evidence that India’s current regime has already reduced the size of its developer community, weakened Devcon participation or caused blockchain companies to relocate. It also contains no government response to Buterin’s comments and does not describe any proposed change to the 30% tax on crypto gains or the 1% TDS on transfers. Those limits are important. The argument for reform is presented by a prominent technology founder, but the available material does not establish the scale of the problem through independent data.
What the report does establish is the presence of competing signals in India’s technology landscape. On one side is strong interest in open technology and an established developer community, conditions that Buterin cited as reasons for holding Devcon in Mumbai. On the other is a tax regime that he believes could make experimentation more difficult, particularly for smaller developers. The country’s ability to turn interest into locally built infrastructure may depend on how those two signals are reconciled.
The debate also reveals a classification challenge for regulators. Blockchain can describe a technical architecture, while crypto refers to assets and transactions that may use that architecture. When regulation focuses on the asset, it may not fully capture the different economic functions of the underlying technology. At the same time, a broader exemption system would need to distinguish genuine development activity from transactions presented as experimentation. The supplied report does not set out how such a distinction could be administered, and no official framework for doing so is cited.
For India’s urban technology ecosystem, the immediate issue is not whether blockchain will replace existing digital infrastructure. There is no evidence in the report to support that conclusion. The more grounded question is whether the country’s regulatory system can accommodate experimentation around technologies that may eventually interact with public payments and government services. That question involves tax authorities, technology policymakers, public institutions, developers and the users of digital services.
Buterin’s remarks therefore amount to a policy signal rather than proof of an established trend. They identify a possible friction between India’s ambition to support open, locally built technology and the transaction rules governing crypto assets. The available evidence confirms the concern has been raised at a major global developer conference in Mumbai. It does not yet show how widely the concern is shared, how much economic activity is affected or whether the government intends to respond.
Those unanswered questions will determine whether the discussion moves beyond criticism of the existing tax regime. The next meaningful developments would be an official response, evidence on the compliance burden faced by smaller developers, or a policy proposal that distinguishes blockchain experimentation from crypto-asset trading. Until then, India’s opportunity to become a centre for core blockchain infrastructure remains an ambition being tested against the practical rules of its digital economy.