Safeheron says it has processed more than $300 billion in digital asset transactions for over 260 institutions without reported fund losses to date. But Adam Dai, the company's General Manager of East Asia, believes that a strong security record alone is not enough to win the confidence of institutional clients.
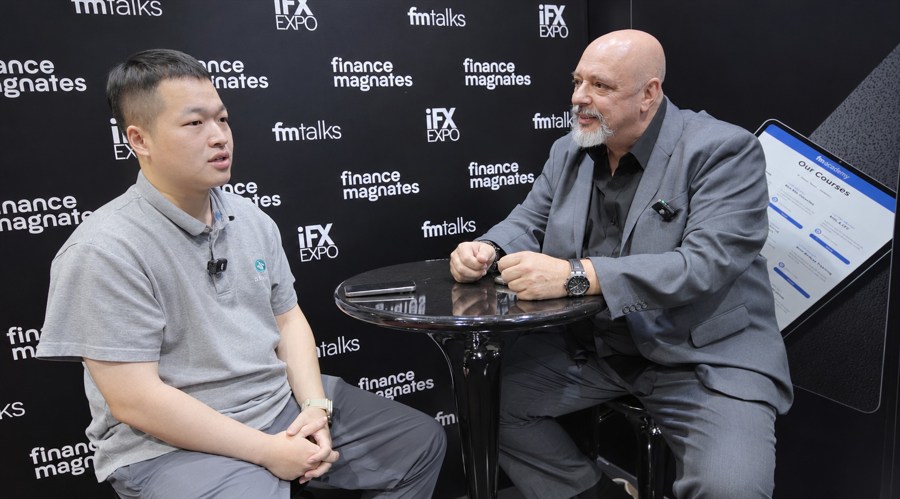
Speaking with Nick Assimenos, Senior Business Development Manager at Finance Magnates, in Hong Kong, Dai discussed Safeheron's approach to institutional crypto custody, the growing use of stablecoins for payments and settlement, and the challenges facing businesses adopting digital assets.
He also explained why open-source security technology, control over digital assets and more consistent compliance standards will be important as stablecoins become more widely used in financial services.
Why Safeheron Focuses on Institutional Crypto Self-Custody
Safeheron provides self-custody multi-party computation (MPC) wallets and wallet-as-a-service infrastructure for institutional clients, including payment service providers, digital banks, compliant exchanges, OTC trading desks and financial institutions involved in stablecoin operations.
According to Dai, the company's relatively low public profile is a deliberate choice, reflecting its focus on institutional security rather than retail recognition.
Its clients can integrate wallet infrastructure into their own platforms through APIs, manage digital assets internally and configure transaction policies and approval workflows according to their operational requirements.
A central part of Safeheron's approach is making its underlying security technology available for examination. The company has open-sourced its MPC cryptography and trusted execution environment (TEE) framework, allowing developers and security specialists to inspect the code through GitHub.
Dai also pointed to independent security audits as part of the company's approach to demonstrating the reliability of its infrastructure. For Safeheron, confidence in its technology should come from technical verification and client experience rather than public marketing.
How Safeheron's Self-Custody MPC Wallets Give Institutions Control
One of the main distinctions Dai highlighted was the level of control institutions retain over their digital assets when using Safeheron's infrastructure.
"We can never control your assets. You have 100% control over your assets," Dai said, explaining the company's self-custody model.
Under this arrangement, institutions retain control of their digital assets while using Safeheron's technology to establish internal transaction controls. These include assigning different permissions to team members, configuring approval processes and defining policies governing how funds can be transferred.
The system is designed to provide a unified management experience, similar to institutional banking, while allowing businesses to maintain control over their cryptocurrency holdings.
Why Security Verification Matters Beyond Transaction Volumes
Safeheron's reported record of processing more than $300 billion in digital asset transfers without fund losses was another point of discussion.
While this track record can help establish credibility with regulated financial institutions, Dai acknowledged that past performance alone cannot demonstrate future security. Prospective clients still need to examine the underlying technology and test how it operates before integrating it with their existing financial systems.
To support this process, Safeheron offers sandbox access and open-source MPC technology, allowing institutional technology teams to assess the infrastructure before deployment.
The distinction is important to the company's approach: transaction history may support confidence, but institutions must also be able to examine the technology behind it.
Stablecoin Payments Are Moving Beyond Crypto Trading
The growing use of stablecoins for commercial transactions was another major theme of the interview. Over the past 18 months, Dai has observed increasing interest from financial institutions and payment companies in using digital assets for payments and settlement rather than primarily as trading instruments.
He pointed to companies such as Visa, Mastercard and Stripe exploring cryptocurrency payments as examples of broader institutional involvement.
Stablecoins are also finding applications in cross-border payments, corporate treasury management and consumer spending through crypto-linked cards.
For businesses, one example involves transferring stablecoins such as USDT and USDC to payment service providers, which can then facilitate payments in traditional currencies, including US dollars and euros, directly to bank accounts. This creates an alternative process for international payments and settlement, with the potential to reduce the time involved in certain transactions.
Among Safeheron's own payment service provider clients, Dai has observed growing activity and wallet usage, reinforcing his expectation that stablecoin payments will continue expanding.
"I think the shift is already happening," he said.
Despite this progress, Dai believes there is considerable room for further growth as more institutions explore practical applications for digital assets.
Managing Digital Assets Across Multiple Wallets and Blockchains
As stablecoin payments become more widely used, managing funds across different wallets, blockchain networks and business entities presents an operational challenge.
Dai noted that institutions often maintain separate cryptocurrency balances for payment processing, reserves and transfers to clients or suppliers. With funds distributed across multiple accounts, monitoring available balances and coordinating transactions can become increasingly complicated.
Safeheron addresses this through a unified digital asset management system, allowing institutions to monitor wallets and manage cryptocurrency holdings from one place. Businesses can identify which wallets serve particular markets, payment activities or operational functions, providing internal teams with a clearer overview of their digital asset balances.
The discussion also covered payment providers developing integrated services that bring cryptocurrency holdings, traditional bank accounts and crypto-linked payment cards together, with self-custody wallet infrastructure such as Safeheron’s serving as the digital asset layer.
These solutions could become increasingly relevant as businesses look for ways to manage traditional and digital currencies through connected financial infrastructure.
Hong Kong Stablecoin Regulation: Progress and Remaining Challenges
Hong Kong's approach to stablecoin regulation has provided greater clarity for issuers, but some digital asset businesses continue to face uncertainty over regulatory requirements and banking access.
The city introduced its stablecoin issuer licensing regime on 1 August 2025, establishing requirements for businesses issuing specified fiat-referenced stablecoins.
Dai sees this as a positive development for stablecoin issuers, while identifying continuing challenges for other market participants, particularly payment service providers and OTC trading desks.
As the regulatory frameworks affecting these businesses continue to take shape, many are looking for further clarity before scaling their Hong Kong operations.
Banking access presents another obstacle. Some digital asset businesses, including firms that hold regulatory licences, encounter difficulties opening local bank accounts because of banks' onboarding requirements. Greater transparency into digital asset operations, such as clearly segregated wallets and auditable transaction policies, could help banks onboard these firms with greater confidence.
For companies seeking to establish operations in Hong Kong, these challenges can create practical barriers even as the regulatory framework for stablecoin issuance becomes more defined.
Why Stablecoin Adoption Still Needs Common Compliance Standards
Looking ahead to the next two or three years, Dai sees inconsistent institutional compliance requirements as one of the obstacles to wider stablecoin adoption.
A transaction involving USDC, for example, may be accepted by one financial institution but rejected by another because their anti-money laundering (AML) and know-your-customer (KYC) assessments reach different conclusions.
This inconsistency creates friction between institutions, complicating transfers and settlement processes that would otherwise be straightforward.
Greater alignment in compliance standards and transaction assessment procedures could help reduce these difficulties, although establishing common practices across different financial institutions remains a challenge.
Security awareness is another concern. Dai believes many institutions entering digital assets still lack the knowledge or tools needed to manage digital assets confidently, potentially slowing broader adoption.
Safeheron's role is to provide institutions with self-custody infrastructure, configurable transaction policies and security controls to support their digital asset operations.
However, technological infrastructure is only part of the solution. More consistent compliance practices and a user experience comparable to traditional banking will also be important if stablecoins are to become a more established part of everyday financial services.
Watch the Full Interview
This article covers the main themes of Finance Magnates' conversation with Adam Dai, General Manager of East Asia at Safeheron.
Watch the full interview to hear:
Why Safeheron prioritises open-source security technology and institutional verification over public visibility.
How payment providers are using stablecoins for cross-border settlements and digital asset management.
What Dai sees as the remaining regulatory, banking and compliance barriers to wider stablecoin adoption.
Why Safeheron prioritises open-source security technology and institutional verification over public visibility.
How payment providers are using stablecoins for cross-border settlements and digital asset management.
What Dai sees as the remaining regulatory, banking and compliance barriers to wider stablecoin adoption.
▶ Watch the full Finance Magnates interview for Dai's complete perspective on institutional digital asset infrastructure and the future of stablecoin payments.
Safeheron says it has processed more than $300 billion in digital asset transactions for over 260 institutions without reported fund losses to date. But Adam Dai, the company's General Manager of East Asia, believes that a strong security record alone is not enough to win the confidence of institutional clients.
Speaking with Nick Assimenos, Senior Business Development Manager at Finance Magnates, in Hong Kong, Dai discussed Safeheron's approach to institutional crypto custody, the growing use of stablecoins for payments and settlement, and the challenges facing businesses adopting digital assets.
He also explained why open-source security technology, control over digital assets and more consistent compliance standards will be important as stablecoins become more widely used in financial services.
Why Safeheron Focuses on Institutional Crypto Self-Custody
Safeheron provides self-custody multi-party computation (MPC) wallets and wallet-as-a-service infrastructure for institutional clients, including payment service providers, digital banks, compliant exchanges, OTC trading desks and financial institutions involved in stablecoin operations.
According to Dai, the company's relatively low public profile is a deliberate choice, reflecting its focus on institutional security rather than retail recognition.
Its clients can integrate wallet infrastructure into their own platforms through APIs, manage digital assets internally and configure transaction policies and approval workflows according to their operational requirements.
A central part of Safeheron's approach is making its underlying security technology available for examination. The company has open-sourced its MPC cryptography and trusted execution environment (TEE) framework, allowing developers and security specialists to inspect the code through GitHub.
Dai also pointed to independent security audits as part of the company's approach to demonstrating the reliability of its infrastructure. For Safeheron, confidence in its technology should come from technical verification and client experience rather than public marketing.
How Safeheron's Self-Custody MPC Wallets Give Institutions Control
One of the main distinctions Dai highlighted was the level of control institutions retain over their digital assets when using Safeheron's infrastructure.
"We can never control your assets. You have 100% control over your assets," Dai said, explaining the company's self-custody model.
Under this arrangement, institutions retain control of their digital assets while using Safeheron's technology to establish internal transaction controls. These include assigning different permissions to team members, configuring approval processes and defining policies governing how funds can be transferred.
The system is designed to provide a unified management experience, similar to institutional banking, while allowing businesses to maintain control over their cryptocurrency holdings.
Why Security Verification Matters Beyond Transaction Volumes
Safeheron's reported record of processing more than $300 billion in digital asset transfers without fund losses was another point of discussion.
While this track record can help establish credibility with regulated financial institutions, Dai acknowledged that past performance alone cannot demonstrate future security. Prospective clients still need to examine the underlying technology and test how it operates before integrating it with their existing financial systems.
To support this process, Safeheron offers sandbox access and open-source MPC technology, allowing institutional technology teams to assess the infrastructure before deployment.
The distinction is important to the company's approach: transaction history may support confidence, but institutions must also be able to examine the technology behind it.
Stablecoin Payments Are Moving Beyond Crypto Trading
The growing use of stablecoins for commercial transactions was another major theme of the interview. Over the past 18 months, Dai has observed increasing interest from financial institutions and payment companies in using digital assets for payments and settlement rather than primarily as trading instruments.
He pointed to companies such as Visa, Mastercard and Stripe exploring cryptocurrency payments as examples of broader institutional involvement.
Stablecoins are also finding applications in cross-border payments, corporate treasury management and consumer spending through crypto-linked cards.
For businesses, one example involves transferring stablecoins such as USDT and USDC to payment service providers, which can then facilitate payments in traditional currencies, including US dollars and euros, directly to bank accounts. This creates an alternative process for international payments and settlement, with the potential to reduce the time involved in certain transactions.
Among Safeheron's own payment service provider clients, Dai has observed growing activity and wallet usage, reinforcing his expectation that stablecoin payments will continue expanding.
"I think the shift is already happening," he said.
Despite this progress, Dai believes there is considerable room for further growth as more institutions explore practical applications for digital assets.
Managing Digital Assets Across Multiple Wallets and Blockchains
As stablecoin payments become more widely used, managing funds across different wallets, blockchain networks and business entities presents an operational challenge.
Dai noted that institutions often maintain separate cryptocurrency balances for payment processing, reserves and transfers to clients or suppliers. With funds distributed across multiple accounts, monitoring available balances and coordinating transactions can become increasingly complicated.
Safeheron addresses this through a unified digital asset management system, allowing institutions to monitor wallets and manage cryptocurrency holdings from one place. Businesses can identify which wallets serve particular markets, payment activities or operational functions, providing internal teams with a clearer overview of their digital asset balances.
The discussion also covered payment providers developing integrated services that bring cryptocurrency holdings, traditional bank accounts and crypto-linked payment cards together, with self-custody wallet infrastructure such as Safeheron’s serving as the digital asset layer.
These solutions could become increasingly relevant as businesses look for ways to manage traditional and digital currencies through connected financial infrastructure.
Hong Kong Stablecoin Regulation: Progress and Remaining Challenges
Hong Kong's approach to stablecoin regulation has provided greater clarity for issuers, but some digital asset businesses continue to face uncertainty over regulatory requirements and banking access.
The city introduced its stablecoin issuer licensing regime on 1 August 2025, establishing requirements for businesses issuing specified fiat-referenced stablecoins.
Dai sees this as a positive development for stablecoin issuers, while identifying continuing challenges for other market participants, particularly payment service providers and OTC trading desks.
As the regulatory frameworks affecting these businesses continue to take shape, many are looking for further clarity before scaling their Hong Kong operations.
Banking access presents another obstacle. Some digital asset businesses, including firms that hold regulatory licences, encounter difficulties opening local bank accounts because of banks' onboarding requirements. Greater transparency into digital asset operations, such as clearly segregated wallets and auditable transaction policies, could help banks onboard these firms with greater confidence.
For companies seeking to establish operations in Hong Kong, these challenges can create practical barriers even as the regulatory framework for stablecoin issuance becomes more defined.
Why Stablecoin Adoption Still Needs Common Compliance Standards
Looking ahead to the next two or three years, Dai sees inconsistent institutional compliance requirements as one of the obstacles to wider stablecoin adoption.
A transaction involving USDC, for example, may be accepted by one financial institution but rejected by another because their anti-money laundering (AML) and know-your-customer (KYC) assessments reach different conclusions.
This inconsistency creates friction between institutions, complicating transfers and settlement processes that would otherwise be straightforward.
Greater alignment in compliance standards and transaction assessment procedures could help reduce these difficulties, although establishing common practices across different financial institutions remains a challenge.
Security awareness is another concern. Dai believes many institutions entering digital assets still lack the knowledge or tools needed to manage digital assets confidently, potentially slowing broader adoption.
Safeheron's role is to provide institutions with self-custody infrastructure, configurable transaction policies and security controls to support their digital asset operations.
However, technological infrastructure is only part of the solution. More consistent compliance practices and a user experience comparable to traditional banking will also be important if stablecoins are to become a more established part of everyday financial services.
Watch the Full Interview
This article covers the main themes of Finance Magnates' conversation with Adam Dai, General Manager of East Asia at Safeheron.
Watch the full interview to hear:
Why Safeheron prioritises open-source security technology and institutional verification over public visibility.
How payment providers are using stablecoins for cross-border settlements and digital asset management.
What Dai sees as the remaining regulatory, banking and compliance barriers to wider stablecoin adoption.
Why Safeheron prioritises open-source security technology and institutional verification over public visibility.
How payment providers are using stablecoins for cross-border settlements and digital asset management.
What Dai sees as the remaining regulatory, banking and compliance barriers to wider stablecoin adoption.
▶ Watch the full Finance Magnates interview for Dai's complete perspective on institutional digital asset infrastructure and the future of stablecoin payments.