Gift
Share
CADD, a Canadian-dollar crypto asset whose backers include Shopify, Wealthsimple and National Bank, is the first stablecoin that securities regulators say does not have to register with them, a decision that grants it a major advantage.
In a joint decision, Canada’s provincial securities regulators said Wealthsimple can offer stablecoins—crypto tokens pegged to the value of a central bank currency—that have not filed paperwork with them as long as the digital assets are issued by Canadian financial institutions. The decision names CADD, a Canadian dollar stablecoin issued by an Alberta trust company, as an example.
Talking Points
- Canada’s provincial securities regulators jointly said Wealthsimple can offer stablecoins—crypto tokens pegged to the value of a central bank currency—that have not filed paperwork with them, as long as the digital assets are issued by Canadian financial institutions
- The decision names CADD, a Canadian dollar stablecoin issued by an Alberta trust company and backed by Shopify, Wealthsimple and National Bank, as an example
- That will reassure merchants and businesses that they can use CADD for payments without running afoul of securities law, said Wealthsimple chief legal officer Blair Wiley, giving it an advantage over competitors that don’t enjoy the same exemption
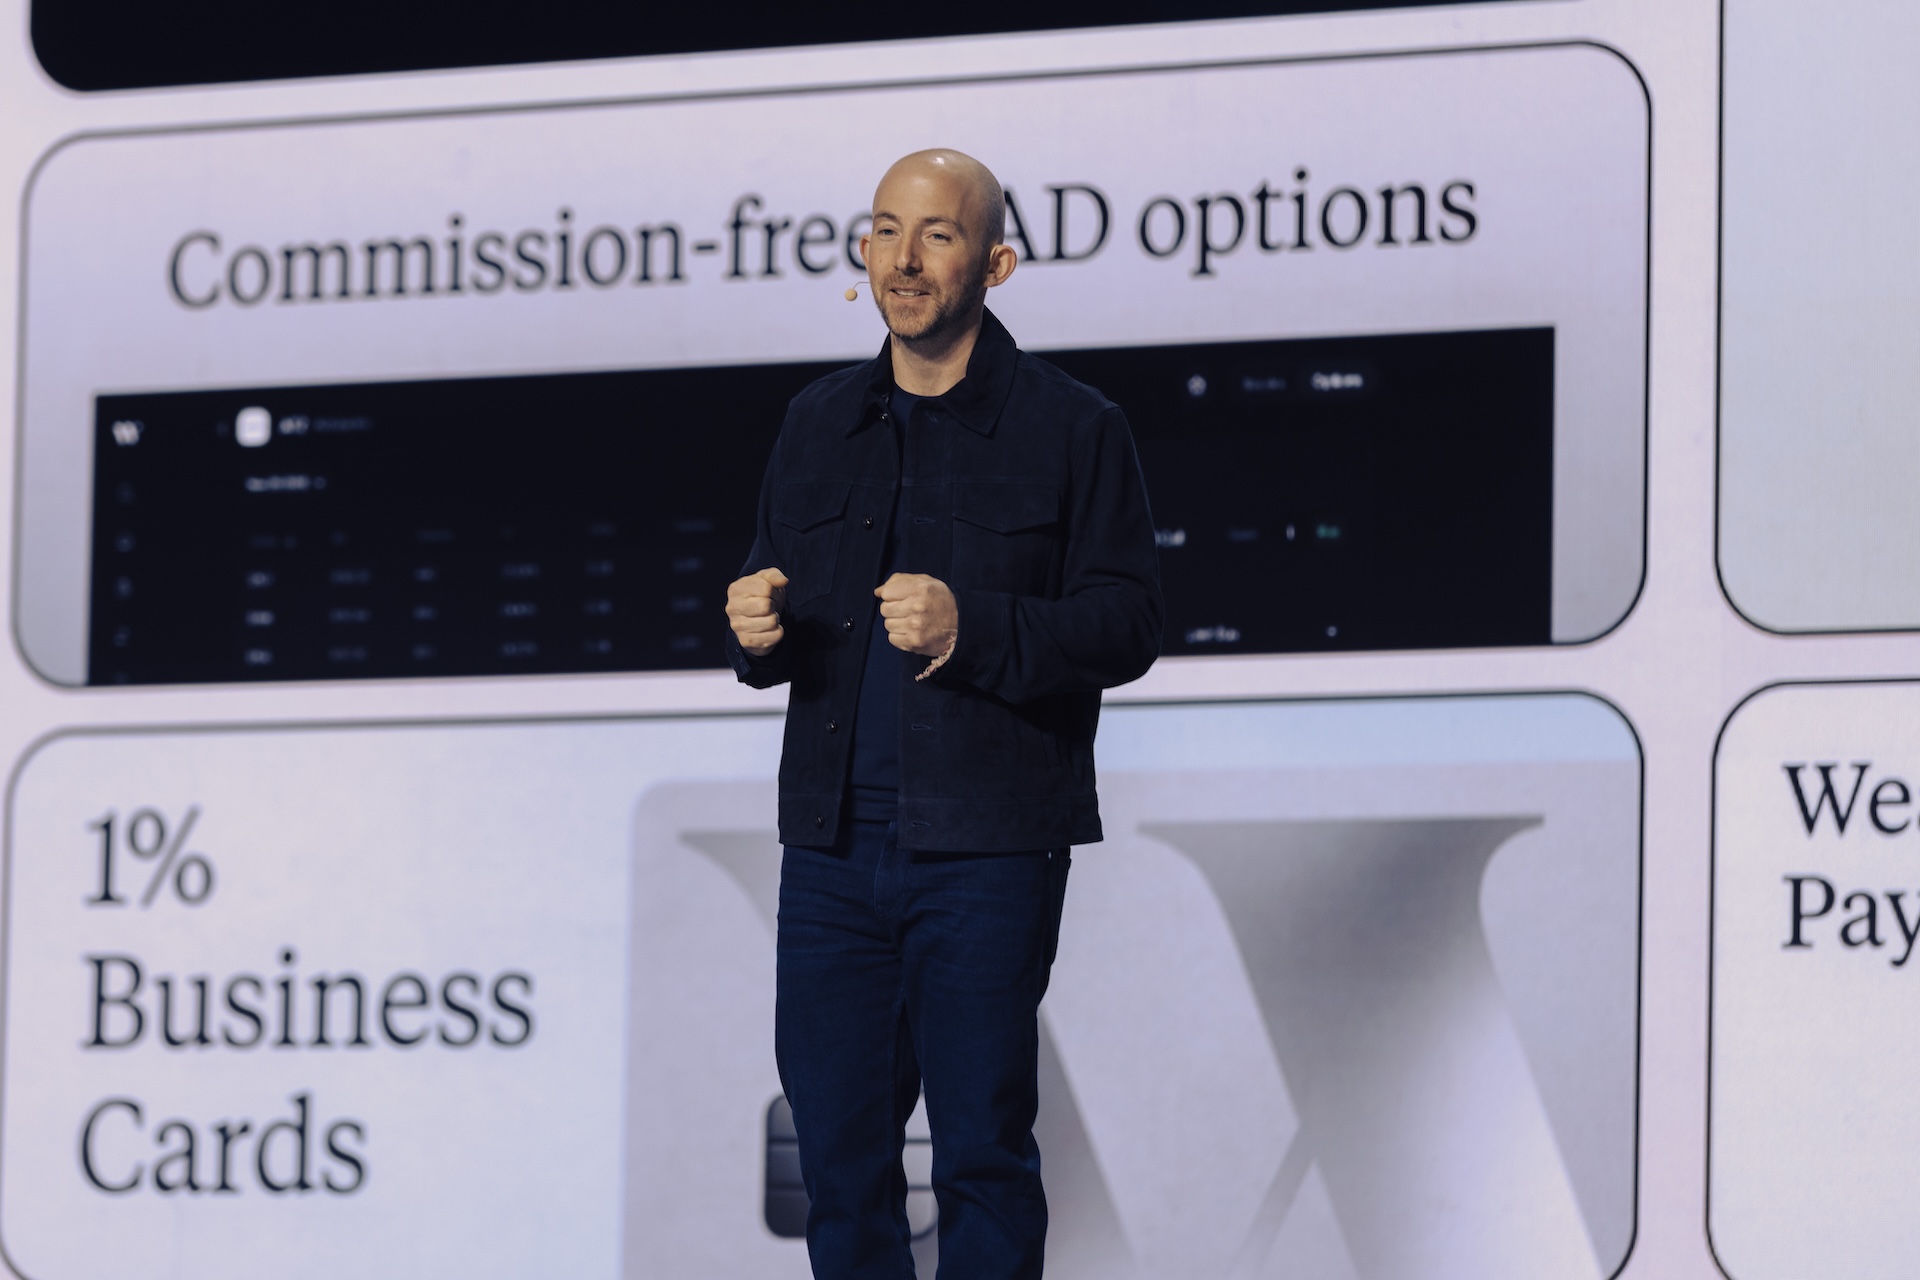
Blair Wiley, chief legal officer for Wealthsimple, said the decision paves the way for businesses to use CADD for payments and settlement without worrying about running afoul of registration requirements, investor protection rules and tax obligations. “That’s a meaningful development and answers some of the hesitation that some businesses have shared about adopting stablecoins,” he said.
The Ontario Securities Commission deferred to the Canadian Securities Administrators (CSA), an umbrella organization for provincial securities regulators, when asked if it agrees with that interpretation of the decision. In an emailed statement, CSA spokesperson Ilana Kelemen confirmed financial institutions don’t have to register as securities dealers or file prospectuses to issue stablecoins, but did not comment on what that means for CADD’s adoption as a payment instrument.
A lot is riding on the question of whether or not stablecoins are securities. The U.S. Securities and Exchange Commission has said stablecoins generally do not fall under its purview, making it much easier for American companies to offer products and services that take advantage of stablecoins’ speed and low cost. Meanwhile, in Canada, regulators have said the opposite—that stablecoins generally are considered securities. The Canadian crypto industry has argued that puts Canada at a disadvantage, possibly with grave implications for the economy and monetary policy if U.S. dollar stablecoins take off as mainstream payment instruments.
Related Articles
National Bank backs Canadian dollar stablecoin in crypto first
Canada’s banks are about to get hit by a trillion-dollar stablecoin tsunami
To complicate matters further, Ottawa plans to put federal legislation governing stablecoins into effect in the fall of 2027. According to a document from the Department of Finance, securities regulators will continue to oversee stablecoins sold and traded on crypto-trading platforms and through investment dealers, while the Bank of Canada will supervise stablecoins used for payments. In their budget earlier this month, the federal Liberals said banks and other federally regulated financial institutions won’t be allowed to issue stablecoins directly.
Tetra Trust, which issues CADD, is a financial institution but not a federally regulated one. It’s a trust company overseen by the Alberta Treasury Board and Finance, putting it in a “special position,” according to CEO Didier Lavallée. Regardless, he said Tetra Trust hasn’t ruled out registering with either the securities regulators or the Bank of Canada. “We’re evaluating all our options, but we do have the optionality to go different ways,” he said.
CADD’s main competitors, QCAD and CADC, have registered with securities regulators. So has Circle, issuer of the U.S. dollar stablecoin USDC.
Wiley said he’s not sure exactly how Wealthsimple customers will use CADD now that it’s available on the Wealthsimple platform. Possible uses include holding a balance to take advantage of the 3.25 per cent rewards rate, making business transactions or sending it abroad to family and friends, he said.
It remains unclear which stablecoin activities are regulated by securities watchdogs and which fall under the Bank of Canada’s authority. Wiley said the industry is likely in for some headaches under two new regulatory regimes that may sometimes overlap.
“I think that over time we will figure this out, and common practices will emerge,” he said. “But I think there will be a difficult period as we make this transition.”
Sponsored Content
The road to risk-smart regulation
Why cybersecurity needs to match pace with AI
How to shift your workforce from AI experimentation to adoption
Loading...
You have shared 5 articles this month and reached the maximum amount of shares available.
If you would like to purchase a sharing license please contact The Logic support at [email protected].
Upgrade to all-access now
You have gifted 0 article(s) this month and have 5 remaining.
Recipients will be able to read the full text of the article after submitting their email address. They will not have access to other articles or subscriber benefits.