Sunstone Hotel Investors (NYSE: SHO) reported third-quarter results on 6 November 2026 that beat Wall Street estimates and prompted a third consecutive increase to its full-year outlook.
Net income attributable to common stockholders came to $38.7m, or $0.21 per diluted share, against a net loss of $2.9m, or $(0.02) a share, in the same quarter last year, according to the company’s results statement.
Sunstone Hotel Investors guidance lifted for third straight quarter
Adjusted funds from operations per diluted share rose 17.6% to $0.20, while adjusted EBITDAre climbed 8.8% to $54.5m, the company said. Revenue of $233.7m beat the average analyst estimate of $223.0m, according to GuruFocus, which tracked the beat against consensus.
Sunstone raised its 2026 adjusted FFO per diluted share guidance to a range of $1.00 to $1.03, up from the $0.88 to $0.96 range set after second-quarter results, as first reported by Seeking Alpha. That second-quarter range had itself marked an increase from the figure management gave after the first quarter, filings show.
Separately, Sunstone’s earnings beat was echoed across coverage: Investing.com put the FFO beat at roughly $0.15 a share versus consensus.
Buybacks fund by hotel sale proceeds
The company repurchased $117.8m of common and preferred stock in the quarter, taking year-to-date buybacks through 5 November to $196.9m, leaving $310.6m under its $500m authorisation, filings show.
Common stock purchases accounted for 9,368,434 shares bought at an average $10.99, for $103.0m. Sunstone also bought back Series H preferred stock – 330,119 shares at $22.30, for $7.4m, a 13.9% discount to liquidation value – and Series I preferred stock, 344,439 shares at $21.69 for $7.5m, a 17.7% discount, according to the 8-K filing.
The board restored the $500.0m repurchase authorisation in February 2026, according to Sunstone’s third-quarter 10-Q. Buybacks this year have drawn partly on proceeds from the sale of the Hyatt Regency San Francisco, a pattern that has now run through three consecutive quarterly releases, each carrying similar language on “accretive” common and preferred repurchases alongside a guidance increase.
A recovery from a lossmaking year-ago quarter
The scale of the year-on-year swing stands out against Sunstone’s recent run of quarterly filings. Diluted earnings per share were $0.08 in the first quarter of 2026 and $0.14 in the second, both filed with the SEC, before climbing to $0.21 in the third. A year earlier, the pattern ran in the opposite direction: EPS of $0.01 in the first quarter of 2025, $0.03 in the second, and a loss of $(0.02) in the third, according to Sunstone’s 2025 10-Q filings. Quarterly revenue has also been uneven: $259.7m in the first quarter of 2026 and $277.1m in the second, both ahead of the $233.7m booked in the third, reflecting the seasonal pattern typical of the hotel REIT’s portfolio.
One data point jarred with the rest of the coverage. A snapshot distributed via the Associated Press cited an average analyst estimate of 53 cents per share, a figure that does not reconcile with the $0.21 GAAP diluted EPS or $0.20 adjusted FFO per share Sunstone actually reported.
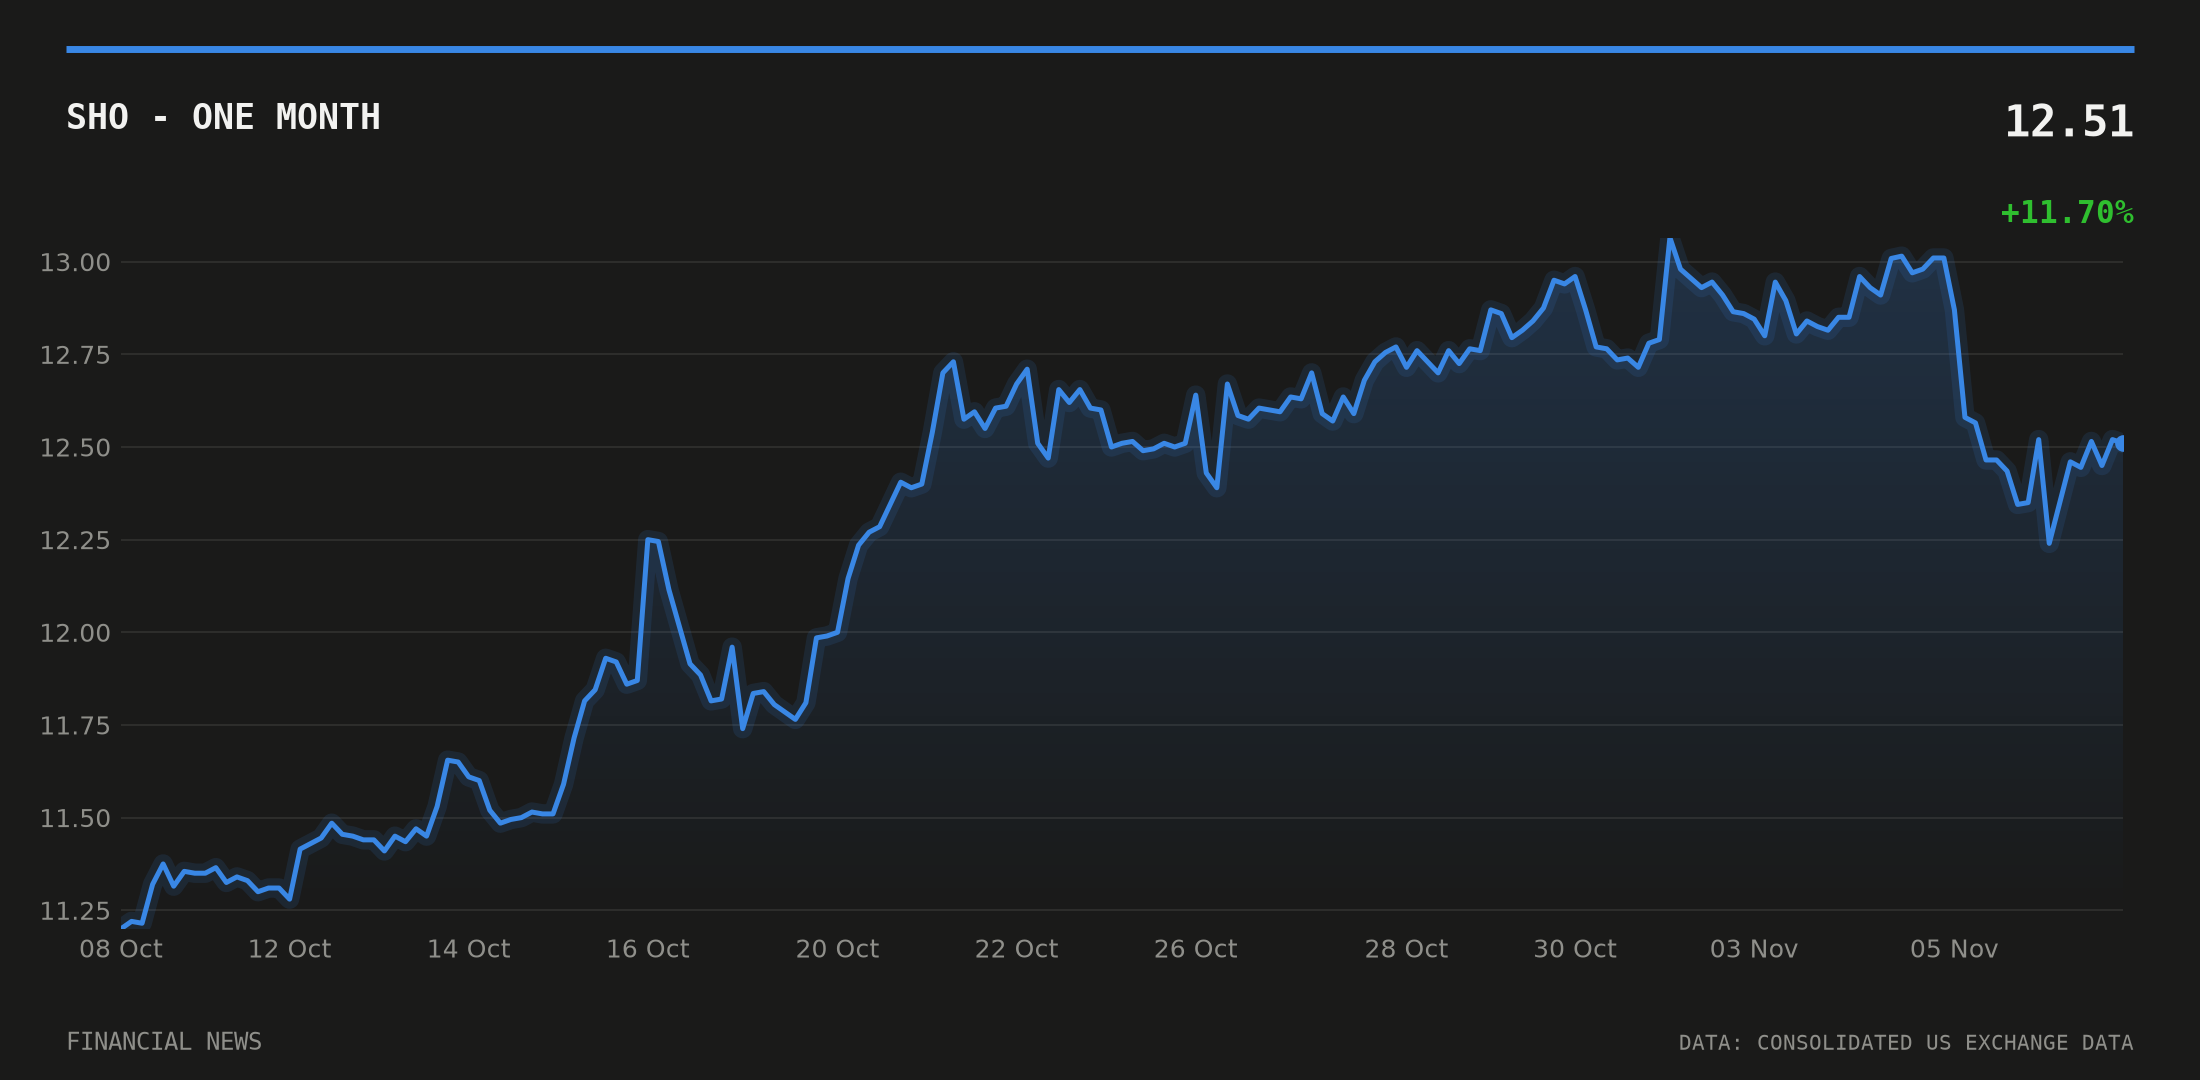
Shares closed at $12.51 on 6 November, up 2.21% on the day and 4.6% over 20 days, trading within a 20-day range of $11.74 to $13.065, according to consolidated exchange data. Volume was roughly in line with the 20-day average. FINRA short-sale data showed SHO’s daily short ratio moving between 0.46 and 0.66 in the fortnight around the results, a range that shows no clear build-up of bearish positioning ahead of the print.
Rate backdrop eases slightly
The 10-year US Treasury yield stood at 4.84% on 5 November, down from 4.90% previously, according to Federal Reserve data. Lower long-term yields matter for hotel REITs such as Sunstone because they bear on refinancing costs and capitalisation rates used to value hospitality assets, a backdrop management referenced in discussing capital allocation on the earnings call.
Sunstone’s three straight quarterly guidance increases in 2026, paired with its opportunistic buyback programme, give investors a marker to track into next year: whether the pace of asset-sale-funded repurchases, including preferred stock bought at discounts approaching 18% to liquidation value, continues once the current authorisation nears exhaustion.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.